
Blogs
Integrated Workforce Mobility Market: Why the 10.25% CAGR Reshapes Global Strategy
By pmarketresearch, 2026-09-18
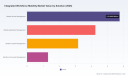
The Integrated Workforce Mobility Market: Strategic Trends and Commercial Opportunities in a Hyperconnected Era
The integrated workforce mobility market has evolved from a niche compliance function into a central pillar of global talent strategy. Valued at 14.5 billion USD in 2025, the market has expanded consistently over the past five years, reflecting a fundamental shift in how organizations deploy, manage, and retain international talent. Looking ahead to 2032, the trajectory points toward sustained expansion, with a compound annual growth rate of 10.25 percent positioning the sector well above many legacy enterprise software categories. This growth is not merely a function of rising cross-border assignments; it signals a deeper restructuring of work itself, where mobility platforms, compliance infrastructure, and digital work environments converge to support distributed, hybrid, and remotely hosted teams.
PW Consulting Information & Electronics Research Center
Yet the market operates at a structural inflection point. Organizations are increasingly caught between the operational imperative to move talent quickly and the regulatory reality of tightening border controls, data privacy mandates, and social security scrutiny. At the same time, the technology stack supporting workforce mobility is fragmenting across device management, application governance, content security, and identity controls, forcing enterprises to reconcile point solutions with integrated platforms. A third tension lies in talent economics: companies must balance cost discipline with the need to offer seamless relocation, cultural integration, and digital onboarding experiences that actually retain high-value assignees. These challenges do not signal market weakness; rather, they define where value will concentrate over the next cycle.
Market Definition and Structural Realities
The integrated workforce mobility market encompasses the technologies, advisory services, and managed programs that enable organizations to deploy employees across borders, manage remote workforces, and comply with immigration, tax, and data security requirements. Historically anchored by global assignment administration, the category has broadened to include digital platforms that orchestrate compliance workflows, payroll alignment, device provisioning, and employee experience touchpoints. The revenue base of 14.5 billion USD in 2025 reflects a market that has moved beyond cyclical assignment volumes and now captures recurring platform usage, managed services, and enterprise-grade security tooling that supports distributed work.
North America remains the largest demand center, reflecting the depth of multinational headquarters, the scale of technology-driven talent strategies, and the maturity of compliance and mobility service ecosystems. Europe follows as a substantial market, shaped by cross-border labor frameworks, high assignment density, and increasingly complex social security coordination. Asia Pacific has emerged as a fast-growing region, driven by intra-Asia talent flows, expanding shared services hubs, and the rapid digitization of HR and mobility operations. Latin America and the Middle East and Africa represent smaller but strategically important pools, often tied to regional headquarters relocation, nearshoring initiatives, and specialized project deployments. The regional mix underscores a clear reality: demand is global, but compliance intensity, infrastructure readiness, and talent availability vary widely enough to require localized execution even within unified platforms.
Deployment patterns further illustrate the market’s direction. Cloud-based delivery now dominates, favored for its scalability, faster integration with HR and identity systems, and ability to support rapid policy updates across jurisdictions. On-premises deployments persist in environments with stringent data residency, legacy infrastructure, or highly regulated operational requirements, but their relative share highlights the broader shift toward cloud-native architectures that can absorb new compliance rules and remote work scenarios without heavy re-engineering. On the solution side, mobile device management continues to anchor the market, given its role in securing endpoints and enabling secure access for distributed staff. Mobile application management and mobile content management extend that foundation by governing which tools employees can use and how sensitive information is stored, shared, and audited. Identity and access management, while smaller in absolute terms, is increasingly critical because cross-border mobility is only as reliable as the authentication, provisioning, and access governance that sit beneath it.
Core Challenges and Inflection Points
Several structural challenges are reshaping how organizations approach workforce mobility. The first is compliance fragmentation. Digital border systems, tax coordination, and social security scrutiny are intensifying, making it harder to treat mobility as a simple HR workflow. Assignees and remote workers increasingly move through environments where eligibility, withholding, and data handling rules change frequently, and organizations that rely on manual processes face higher compliance risk and slower deployment timelines.
A second challenge is the technology integration gap. Many enterprises still operate disjointed stacks for device management, application security, content controls, and identity governance. This fragmentation creates blind spots in visibility, slows provisioning, and complicates audit readiness. The more distributed the workforce becomes, the more acute the operational penalty of disconnected systems. Integrated platforms that unify policy execution, access controls, and user experience are gaining relevance precisely because they reduce the friction between compliance and productivity.
A third challenge involves talent experience and retention. Cross-border mobility has historically been managed as a cost and risk function, but competitive labor markets are forcing a reframe. Employees expect clear onboarding, supportive relocation experiences, and digital tools that make remote or mobile work seamless. Programs that overemphasize compliance at the expense of user experience risk higher assignment dropout, lower engagement, and weaker long-term workforce planning outcomes. The market is therefore shifting from transactional mobility administration toward experience-led, data-informed talent deployment.
Strategic Drivers Reshaping the Market
The market’s expansion is being propelled by a convergence of technology, policy, and demand-side dynamics. The most consequential driver is the maturation of cloud-native mobility architectures and the broader enterprise tooling ecosystem that supports distributed work. Secure device enrollment, policy-driven application distribution, content encryption, and identity verification are now expected capabilities rather than optional enhancements. These building blocks allow organizations to scale mobility programs without proportionally scaling administrative overhead, and they make it feasible to extend secure work environments to contingent staff, remote hires, and short-term cross-border deployees.
Policy and regulatory evolution is equally influential. Public infrastructure initiatives focused on advanced networks and broadband expansion are reinforcing the connectivity base that distributed work depends on. As legacy copper systems transition toward fiber-based and wireless capacity upgrades, organizations can rely on more consistent data transport for mobility applications, video collaboration, remote access, and location-aware compliance workflows. Alongside infrastructure modernization, regulatory attention on digital border processes and tax/social security coordination is increasing. This does not slow mobility so much as reshape it: programs must be designed with built-in compliance checks, jurisdictional logic, and audit trails, which in turn raises demand for platforms and advisory services that can operationalize those requirements at scale.
Demand-side behavior is shifting as well. Organizations are increasingly treating internal mobility, international assignments, and remote work as interconnected levers in talent strategy rather than separate programs. The rise of hybrid work models has expanded the definition of mobility to include employees who remain in one country but operate across borders digitally, consuming content, collaborating with international teams, and accessing systems that require consistent security and governance. At the same time, employers are seeking better visibility into workforce deployment patterns so they can balance tax efficiency, talent access, and employee experience. Payroll and HR data are increasingly used to optimize mobility program design, helping organizations identify where assignments are underutilized, where compliance costs can be reduced, and where policy adjustments can improve retention.
Cost structure and supply-side dynamics also play a meaningful role. Mobile workforce environments require ongoing management of devices, licenses, security policies, and support workflows. Companies that can consolidate these functions into integrated platforms gain operating leverage, especially when they face high assignment volumes or frequent policy changes across jurisdictions. Managed services further extend this advantage by offloading specialized immigration, tax, and relocation coordination to providers that maintain current regulatory knowledge and operational capacity. In a market where compliance mistakes and employee dissatisfaction both carry real costs, the economic case for integrated mobility solutions is growing stronger.
Competitive Landscape and Differentiation
The competitive environment blends advisory-led service providers, platform-focused specialists, and large technology firms whose tools underpin secure mobility at scale. This mix is one reason the market is both competitive and rapidly evolving: different players compete on service depth, technology breadth, geographic coverage, and employee experience, and the lines between them are increasingly blurred as platforms absorb compliance workflows and service providers invest in digital delivery.
EY occupies a strong position by combining tax, immigration, global compensation, and mobility pathway capabilities with a platform orientation that connects mobility to broader business strategy. Its recent emphasis on trust infrastructure and strategic integration signals a move beyond assignment administration toward the idea that mobility programs must be trusted, transparent, and aligned with enterprise priorities. That positioning matters because cross-border mobility increasingly depends on data governance, employee confidence, and executive sponsorship, not just operational execution.
Vialto Partners differentiates through globally integrated service design, covering immigration, tax, managed services, business travel, and remote work compliance, supported by digital tools such as its myMobility platform. Visibility in industry recognition and published insights on payroll-driven mobility optimization highlights an emphasis on practical program improvement and partnership-driven delivery. In a market where clients want both compliance rigor and user-friendly execution, that combination is a meaningful value proposition.
Mercer continues to leverage its scale in talent mobility services, policy benchmarking, and global mobility program support. Its comparative advantage lies in data-rich benchmarking and structured program design for international assignments and workforce strategy, which helps organizations calibrate policies against peer practice while maintaining compliance and cost discipline.
On the technology side, Microsoft provides the collaboration, cloud, security, and identity foundation that many mobility programs rely on, making it an important enabler of hybrid and remote work at enterprise scale. IBM contributes enterprise mobility management and workforce transformation capabilities, including device and application management tools designed for mobile workforce environments. VMware, now part of Broadcom, offers enterprise mobility management through its workspace and device management solutions, helping organizations secure access across endpoints and applications. Cartus rounds out the field with relocation and global talent mobility services that emphasize employee experience, policy design, and strategic program execution.
The landscape is moving toward tighter integration. Service providers are investing in digital platforms and data-driven insights to improve speed, consistency, and transparency, while technology firms continue to deepen the security, identity, and management layers that make mobility viable at scale. At the same time, new entrants and niche specialists can gain traction by focusing on specific pain points, such as remote work compliance, regional assignment complexity, or employee experience design. The result is a market that is consolidating around integration, yet still open to differentiation by specialty, geography, and service model. Market concentration remains moderate, with a meaningful share held by leading firms but enough fragmentation to reward focused capabilities and strong execution.
Healthcare Workforce Management System Market
Forward Outlook: Trends That Will Shape the Next Cycle
Over the next three to five years, the most consequential trend will be the emergence of mobility as an integrated control plane rather than a set of disconnected workflows. Platforms that combine compliance logic, identity and access governance, device and application management, and employee experience will become the default architecture for organizations managing distributed talent. This matters commercially because it shifts value from manual coordination toward scalable orchestration, where faster provisioning, stronger audit readiness, and better policy consistency become competitive advantages.
A second trend is the increasing use of workforce data to optimize mobility strategy. Payroll, assignment history, compliance outcomes, and employee feedback will be used more systematically to refine policy design, predict cost exposure, and improve assignment success rates. Organizations that treat mobility data as strategic rather than operational will be better positioned to balance talent access, cost control, and retention. This creates opportunities for advisory and technology capabilities that can translate raw data into program decisions.
A third trend is the continuing realignment of compliance expectations around digital borders, data handling, and cross-border employment rules. Rather than reducing mobility, this dynamic will likely accelerate demand for systems and services that embed jurisdictional logic, automate documentation, and support ongoing monitoring. The commercial implication is that mobility programs will need to be designed for adaptability, with policy engines and platform configurations that can absorb regulatory change without full rebuilds.
These trends carry uncertainty. Regulatory direction may diverge by region, technology integration may prove more complex in organizations with legacy systems, and talent expectations may evolve faster than program budgets. Companies that anticipate these variables by building flexible platforms, maintaining compliance visibility, and investing in employee experience will be better placed to convert change into advantage.
Strategic Actions for Decision Makers
For enterprise executives and strategic planning teams, the priority is to treat integrated workforce mobility as a structural capability rather than a periodic administrative need. That means consolidating device, application, content, and identity management into a coherent architecture, aligning mobility programs with broader talent strategy, and using benchmarking and internal data to refine policy design. Organizations that do this early will reduce compliance exposure, improve deployment speed, and strengthen retention in competitive talent markets.
For investors, the opportunity lies in identifying providers and technology layers that can sustain recurring value as mobility programs become more digital and data-driven. Attention should focus on platforms with strong integration potential, clear compliance and security differentiation, and the ability to support both managed services and self-serve enterprise usage. Given ongoing consolidation and specialization, selective exposure to capability leaders and enabling technologies is likely to outperform broad, undifferentiated exposure.
Integrated Smart Toilet Market
For procurement and mobility program owners, the practical task is to evaluate solutions based on integration depth, jurisdictional coverage, employee experience, and operational transparency. Procurement decisions should weigh not only initial cost but also the downstream impact on compliance risk, assignment success, and administrative burden. Detailed segmentation data, vendor comparisons, and tailored program recommendations can materially improve those decisions, especially when the market is changing this quickly.
For detailed analysis of this topic, please visit the official page: Integrated Workforce Mobility Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tongbianling Jiaonang Market 5.85% CAGR: Why 78% China Share Defines 2032 Growth
By pmarketresearch, 2026-09-18
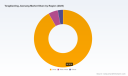
Strategic Trends and Commercial Opportunities in the Tongbianling Jiaonang Market
Market Overview and Core Challenges
The global market for Tongbianling Jiaonang, a traditional Chinese medicine formulation primarily used for constipation relief, has demonstrated steady expansion over the past five years. Valued at approximately USD 85.0 million in 2025, the market is projected to reach USD 126.55 million by 2032, reflecting a compound annual growth rate of 5.85 percent. This trajectory underscores a consistent demand environment supported by demographic shifts, expanding access to over-the-counter traditional medicine, and growing acceptance of TCM-based gastrointestinal solutions in both domestic and select international markets. The growth pattern suggests a maturing yet still expanding ecosystem where volume expansion is gradually complemented by value-oriented formulation upgrades and channel diversification.
Despite this favorable backdrop, the market faces several structural challenges that shape commercial execution and long-term positioning. First, regulatory fragmentation across export destinations remains a persistent friction point. Products that are classified as OTC Class A traditional Chinese medicine under domestic standards encounter varying registration pathways, documentation requirements, and quality verification expectations when entering neighboring healthcare systems. This divergence creates compliance overhead and delays market entry for manufacturers pursuing cross-border distribution. Second, pricing pressure in domestic channels continues to compress margins for value-oriented SKUs. Competitive intensity among regional producers has led to a wide range of generic offerings, making it difficult for mid-tier brands to differentiate solely on formulation familiarity without reinforcing trust signals through quality management, packaging modernization, or clinical positioning. Third, channel migration is reshaping replenishment behavior. While traditional pharmacy networks still account for the majority of sales volume, digital commerce is gaining share among younger adults and urban consumers who prioritize convenience, repeat ordering, and transparent product information. Manufacturers that rely heavily on legacy distribution must adapt inventory planning and promotional design to avoid losing share to more agile players.
Taken together, these dynamics define a market that is growing but not necessarily becoming uniformly more profitable. The key inflection point for stakeholders lies in balancing scale-driven volume expansion with compliance readiness, channel relevance, and brand differentiation. Companies that treat regulatory navigation, pricing architecture, and digital channel engagement as integrated strategic priorities are better positioned to convert top-line growth into sustainable market advantage.
Key Demand Drivers Shaping Market Trajectory
Three interlocking forces are propelling the Tongbianling Jiaonang market forward: formulation and channel innovation, regulatory and policy evolution, and shifting demand-side behavior across patient demographics. Each driver reinforces the others, creating a landscape where commercial success depends on aligning product strategy with both compliance realities and consumer access patterns.
Formulation Innovation and Accessibility Improvements
Innovation in this segment is less about radical new molecular entities and more about optimizing established herbal combinations, improving consistency, and widening access through modern delivery and packaging. Producers are increasingly focusing on batch consistency, label clarity, and usage simplicity to reinforce OTC usability for elderly and long-term users. At the same time, select manufacturers are pursuing international product registration to validate quality standards and open new revenue channels. The successful completion of Indonesian drug registration for Tongbianling Jiaonang in late 2025 illustrates how regulatory validation can unlock export pathways and signal quality assurance to overseas buyers. Such milestones matter because they convert formulation familiarity into defensible market access, especially in countries where consumer interest in TCM-based digestive solutions is rising but regulatory scrutiny remains high.
Policy and Regulatory Environment
Policy dynamics are shaping both domestic confidence and export feasibility. On the domestic side, standardized OTC classification and dosing guidance provide a clear regulatory framework that supports consumer recognition and pharmacy stocking decisions. This clarity reduces uncertainty for retailers and helps maintain steady replenishment cycles. On the international side, however, the absence of uniform registration processes introduces variability. Public advisories in certain markets have highlighted concerns about unregistered imports and the need for local product verification. Rather than representing a fixed barrier, this environment rewards manufacturers that invest early in documentation, quality traceability, and regional compliance alignment. For companies with export ambitions, proactive regulatory planning is becoming a competitive differentiator rather than a back-office function.
Demand-Side Shifts Across Patient Groups
Demand patterns are increasingly influenced by demographic trends and self-care behavior. Elderly consumers represent a substantial share of usage, driven by age-related digestive concerns and habitual constipation management. Adults, including those with sedentary lifestyles or intermittent digestive discomfort, are also contributing to volume growth, particularly where convenience and repeat purchase ease are priorities. This dual demographic base supports a market where both clinical trust and everyday accessibility matter. Consumers are not only seeking symptom relief; they are also evaluating ease of purchase, packaging readability, and the credibility of product origin. As a result, manufacturers that align formulation communication with target user needs and provide clear usage guidance tend to resonate more effectively across both pharmacy and digital channels.
Wallichinine Market
Supply Chain and Cost Structure Dynamics
Supply chain considerations are exerting subtle but important influence on pricing and product availability. The domestic market includes a broad range of generic versions priced at accessible levels, which keeps the category affordable but also intensifies competition on cost. Producers that can manage raw material sourcing, manufacturing consistency, and distribution efficiency are better equipped to defend margins without eroding consumer trust. For export-oriented players, additional cost components such as registration, documentation, and localized quality verification can affect runway and pricing strategy. In this environment, operational discipline and selective scale advantages increasingly determine which manufacturers can compete on both affordability and reliability.
Competitive Landscape and Leading Strategies
The competitive field in the Tongbianling Jiaonang market is shaped by a mix of established domestic producers, regional manufacturers, and players with varying levels of international ambition. Market concentration indicates that a limited number of leading firms control a meaningful share of revenue, but the presence of multiple active producers suggests ongoing competition on formulation reputation, channel access, and pricing. This structure creates both opportunities for consolidation and room for differentiated positioning.
Strategic Positioning Among Leading Players
Leading manufacturers are pursuing distinct strategic postures that reflect their product portfolios, geographic focus, and channel strengths. One active producer holds a prominent position through its association with a widely recognized drug registration code and a formulation built around senna leaf, angelica, and cistanche for constipation relief. Its recent Indonesian drug registration demonstrates a deliberate push into regulated export markets, using compliance achievement as a gateway to international credibility. Another major player markets its product for heat-induced constipation, long-term bedridden constipation, and habitual elderly constipation, with a strong emphasis on international e-commerce distribution. This approach reflects a channel-led expansion strategy that prioritizes reach, repeat purchase convenience, and direct consumer engagement beyond traditional pharmacy networks. Other significant participants contribute to the broader ecosystem by producing related or equivalent TCM constipation formulas, serving clinical and research channels, or maintaining listed-manufacturer status with national-standard specifications. Together, these players illustrate a market where differentiation arises from a combination of formulation narrative, regulatory readiness, channel strategy, and supply reliability.
Worldwide Oblong Jar Market
Differentiation Beyond Price
Because generic alternatives are available at accessible domestic price points, sustained differentiation increasingly depends on trust-building elements rather than cost alone. Manufacturers that can demonstrate consistent quality, clear labeling, and reliable availability are better positioned to defend shelf presence and digital visibility. For international expansion, documented regulatory approvals and adherence to destination-market requirements provide additional credibility. In domestic settings, product education, pharmacy relationships, and packaging clarity can serve as practical differentiators that help brands stand out without relying solely on promotional discounting.
Consolidation, Fragmentation, and New Entry Dynamics
The market appears to be moving toward a dual trajectory. On one hand, larger producers with established compliance infrastructure and broader distribution networks are well placed to capture share from smaller or less organized competitors, especially as regulatory and export requirements become more demanding. On the other hand, regional manufacturers continue to serve local price-sensitive segments, and digital channels lower entry barriers for brands that can compete on convenience and consumer messaging. New entrants or expanding players therefore face a choice: compete on affordability in crowded domestic segments, or invest in compliance and channel capabilities to access higher-value export and digital opportunities. The balance between consolidation and fragmentation will likely depend on how quickly regulatory harmonization progresses in key export markets and how fast digital commerce reshapes purchasing behavior.
Future Outlook and Emerging Trends
Looking ahead to the next several years, the Tongbianling Jiaonang market is likely to be shaped by three major trends, each carrying distinct commercial implications.
Steady Growth with Channel Rebalancing
Market expansion is expected to continue at a moderate pace, supported by demographic demand and broader acceptance of OTC TCM solutions. However, the composition of growth will increasingly shift toward channels that offer convenience, repeat ordering, and stronger consumer data feedback. Manufacturers that align supply planning, packaging, and promotional execution with digital and retail pharmacy dynamics will be better positioned to capture this rebalancing. The commercial opportunity lies not just in selling more units, but in building channel-relevant customer journeys that reduce friction and improve replenishment consistency.
Regulatory Validation as a Market Access Lever
As export interest grows, regulatory approval and quality documentation will become more central to commercial strategy. Milestones such as overseas registration validate product standards and open doors to distributors and retailers who require assurance before stocking imported OTC products. This trend favors manufacturers that treat regulatory investment as a pathway to market access rather than a compliance cost. The related risk is that uneven registration timelines and varying documentation expectations can slow expansion plans, making phased market prioritization and realistic compliance budgeting essential.
Differentiation Through Trust, Clarity, and Consistency
With multiple generic options available, future competition will increasingly reward brands that communicate clear usage guidance, consistent quality, and reliable availability. This is especially relevant for elderly users and caregivers who value straightforward instructions and dependable supply. Companies that strengthen these attributes can limit direct price confrontation and build more resilient demand. At the same time, the risk of advisory notices or quality concerns in unregulated import channels underscores the importance of maintaining strong documentation and respecting destination-market requirements. Commercial players that proactively manage these trust factors will be better insulated against reputation and compliance disruptions.
Strategic Actions for Decision Makers
For manufacturers, the priority is to align product strategy with both domestic affordability and international compliance readiness. This means investing in formulation consistency, documentation rigor, and channel-specific packaging or labeling that supports pharmacy stocking and digital selling. Where export markets are targeted, early regulatory planning and phased geographic prioritization can reduce time-to-access risk while protecting operating margins.
For investors, the market offers exposure to a steadily expanding OTC TCM category, but value creation will depend on selecting operators with credible compliance execution, channel adaptability, and clear differentiation beyond pricing. Due diligence should emphasize regulatory milestones, distribution resilience, and the ability to manage generic competition without eroding brand trust. Companies that combine scale efficiency with targeted international validation are more likely to generate durable returns in a fragmented but growing landscape.
For procurement and distribution stakeholders, the practical focus should be on supply reliability, documentation transparency, and channel fit. Evaluating suppliers on consistency of availability, clarity of product information, and readiness to meet local registration or quality expectations can reduce downstream risk. Building relationships with manufacturers that demonstrate both domestic reach and export discipline provides a stronger foundation for long-term category management. In a market where detailed segment dynamics, pricing structures, and regional access conditions vary meaningfully, comprehensive market intelligence can help decision makers time entry, prioritize segments, and tailor strategy with greater confidence.
PW Consulting Health Care Research Center
For detailed analysis of this topic, please visit the official page: Tongbianling Jiaonang Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Degradable Implants Market: Why 8.25% CAGR and Material Shifts Redefine Growth
By pmarketresearch, 2026-09-18
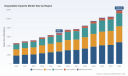
Degradable Implants Market: Stragetic Trends and Commercial Opportunities in the Bioabsorbable Era
1. Market Reality and Core Challenges
The global market for degradable implants has crossed a critical inflection point. Valued at approximately USD 6.85 billion in 2025, the segment has expanded steadily from around USD 4.61 billion in 2020, reflecting a compound annual growth rate of 8.25 percent through 2032. By the end of the forecast window, annual revenue is projected to approach USD 11.93 billion. This trajectory is not merely a function of rising procedural volumes; it reflects a structural shift in how clinicians and health systems evaluate implant performance. The preference is moving away from permanent hardware that requires secondary removal procedures, toward bioabsorbable solutions that support tissue regeneration while gradually transferring load back to native structures.
Despite the growth trajectory, the industry faces several operational and commercial headwinds that shape how value is captured. First, the regulatory bar for bioresorbable devices remains unusually high. Agencies require comprehensive biocompatibility profiling, long-term in vivo degradation tracking, and explicit demonstration of mechanical equivalence throughout the resorption timeline. These requirements extend development cycles and raise the cost of clinical validation, particularly for metallic and polymer systems that behave differently during early inflammation and remodeling phases.
Biodegradable Micro Screws Market
Second, the economics of advanced biomaterials create a narrow margin window. Specialized magnesium alloy development and precision manufacturing currently generate production costs 30-50 percent higher than conventional titanium or stainless-steel implants. Procurement teams accustomed to cost-per-procedure comparisons must reconcile upfront premium pricing with downstream savings from eliminated removal surgeries and reduced revision rates. This value proposition is persuasive in controlled pilot settings, yet it demands robust real-world evidence before widespread formulary adoption.
Third, supply chain concentration introduces pricing volatility and geographic risk. China dominates primary magnesium production, which means medical-grade biodegradable magnesium alloys are exposed to raw material fluctuations and logistics constraints. Manufacturers must navigate this dependency while maintaining strict purity and structural consistency for load-bearing applications. The convergence of these challenges—regulatory rigor, cost premiums, and commodity exposure—means that commercial success depends less on product novelty alone and more on integrated evidence generation, manufacturing discipline, and reimbursement strategy.
2. Key Drivers Reshaping the Market
Technology Innovation and Material Breakthroughs
Material science is the primary engine behind the market's expansion. Polymer-based systems have matured significantly, with self-reinforced PLGA constructs now enabling trauma, pediatric, and extremity applications that were previously limited by mechanical strength concerns. Magnesium alloy implants have emerged as the most disruptive category, combining favorable mechanical compatibility with predictable resorption and bioactive stimulation of bone healing. The ability to offer magnesium-based screws and pins with regulatory clearances has shifted magnesium from a research curiosity to a clinically viable fixation option. These advances are crossing over into cardiovascular scaffolds and soft-tissue repair, where temporary support structures reduce long-term foreign-body concerns. The broader implication is that device manufacturers are no longer choosing between resorbable and permanent hardware on a binary basis; they are engineering degradation profiles to match specific anatomical and clinical timelines.
Regulatory Evolution and Evidence Standards
Regulatory pathways are becoming more defined, but they are also more demanding. Guidance from major agencies now consistently requires ISO 10993 biocompatibility testing, long-term in vivo degradation studies, and demonstration of mechanical equivalence across the degradation window. This framework is simultaneously a barrier and a competitive moat. Companies that build rigorous evidence pipelines early can secure first-mover advantages, while laggards face lengthened development timelines and fewer differentiation points. Recent milestones illustrate the trend: magnesium-based orthopedic implants have achieved landmark clearances in the US and CE marks in Europe, establishing regulatory precedents for metallic bioabsorbable devices. These approvals do not lower the bar; they clarify it. The message to the industry is that evidence design, not just device design, increasingly determines commercial viability.
Demand-Side Shifts and Clinical Economics
Clinical demand is being shaped by two reinforcing forces: procedural preference and total-care economics. Surgeons increasingly favor implants that eliminate the need for secondary removal, particularly in pediatric populations, sports medicine, and trauma cases where revision surgery carries additional risk. At the same time, health systems are scrutinizing downstream costs more closely. A premium-priced bioabsorbable implant can be economically justified when it reduces readmission, revision, and rehabilitation burden. Dental and craniofacial applications further expand the demand base, as temporary fixation and guided bone regeneration benefit from materials that resorb without leaving permanent hardware in aesthetically sensitive sites. This demand evolution is not uniform across regions or service lines; it is strongest where clinical outcomes and total episode cost can be linked through credible evidence.
Supply Chain Dynamics and Manufacturing Capability
Cost structure and supply resilience are becoming strategic differentiators. Medical-grade biodegradable alloys and specialty polymers depend on controlled synthesis, precision machining, and consistent sterilization processes. The concentration of primary magnesium production in specific geographies amplifies pricing exposure and incentivizes manufacturers to diversify sourcing, secure long-term agreements, and invest in internal alloy formulation expertise. Manufacturing scale is not the only concern; consistency is. Slight variations in degradation rate or surface characterization can alter clinical performance and regulatory acceptance. As a result, the supply chain is evolving from a commodity procurement function into a core competency that shapes margin structure, product reliability, and time-to-market.
3. Competitive Landscape and Leading Strategies
The competitive field blends focused specialty innovators with large musculoskeletal and cardiovascular platforms. The landscape is not yet consolidated around a single material class, but it is increasingly segmented by evidence depth, regulatory positioning, and application focus. Understanding how the leading players position themselves helps clarify where value is being created and where openings remain.
Among the specialty innovators, Bioretec has emerged as a notable example of a focused strategy centered on fully absorbable orthopedic implants. The company has pursued regulatory milestones in parallel with portfolio expansion, including CE mark approvals for trauma screw products, FDA Breakthrough Device Designation for a magnesium alloy drill pin, and continued commercialization of PLGA-based Activa implants for trauma and pediatric applications. These moves reflect a deliberate pathway strategy: pair magnesium fixation with polymer options where mechanical or resorption profiles differ, and build an evidence base that spans adults and children. Inion, another Finland-based specialist, has commercialized bioabsorbable and bioactive plates, screws, pins, and anchors across orthopedics, CMF, spine, sports medicine, and dental indications, with a substantial clinical footprint. Inion's approach emphasizes a broad polymer platform and cross-application reuse of material know-how, which allows it to serve multiple surgical specialties while maintaining a coherent product architecture. Syntellix has built its identity around magnesium alloy bioabsorbable screws and pins for orthopedic and trauma fixation, leveraging CE-certified metallic solutions and clinical use across multiple regions. Its positioning underscores the growing credibility of magnesium as a load-bearing resorbable option and the importance of demonstrating real-world fixation performance.
Large players are entering and scaling through complementary strategies. Medtronic offers bioresorbable technologies across orthopedic and cardiovascular applications, including vascular scaffolds and fixation solutions, leveraging broad distribution and clinical networks. Johnson & Johnson, through its medtech division, develops polymer-based bioresorbable fixation systems for orthopedics and CMF, aligning resorbable hardware with established surgical franchises. Stryker and Zimmer Biomet supply bioabsorbable implants and fixation devices for orthopedic trauma and sports medicine, integrating resorbable options into wider product portfolios. Smith+Nephew markets bioabsorbable implants for soft tissue repair and orthopedic applications, where temporary scaffolds can support healing without permanent hardware. In the cardiovascular space, Biotronik has developed resorbable magnesium scaffolds for coronary interventions, illustrating how degradable technology extends beyond fixation into vessel support and remodeling.
PW Consulting Health Care Research Center
Several strategic patterns distinguish the leaders. First, material-platform thinking is replacing single-product tactics. Companies that can adapt a polymer or magnesium base across trauma, pediatrics, CMF, spine, or dental applications gain manufacturing leverage and clinical credibility simultaneously. Second, regulatory positioning is being used as a competitive moat. Early clearances, breakthrough designations, and well-documented degradation data create preference in formulary discussions and surgeon adoption cycles. Third, application breadth versus depth is a deliberate trade-off. Some specialists pursue deep evidence and regulatory traction in a narrow field to command premium positioning, while larger firms use resorbable lines to complement existing franchises and cross-sell into established procedural volumes.
Endosseous Implant Market
The market structure is evolving along three axes. Consolidation is likely in distribution and evidence generation, where scale matters for clinical studies, reimbursement files, and surgeon education. Differentiation is intensifying around degradation control, mechanical performance, and application-specific evidence. New entrants will continue to emerge where there are unmet indications or underserved geographies, but they will face the same evidence and supply expectations that define the leaders. The net effect is a competitive environment where technology alone is insufficient; credible clinical data, manufacturing consistency, and commercial execution determine who captures durable share.
4. Outlook: Three Trends to Watch Over the Next Three to Five Years
The next phase of market evolution will be defined by how companies convert material advances into repeatable commercial value. Three trends are particularly consequential.
1. Evidence-led adoption will become the primary growth lever. As more bioabsorbable products reach mature regulatory status, the differentiation shift moves from approval to adoption. Expect a rising emphasis on prospective registries, comparative studies against permanent hardware, and total-cost-of-care analyses that justify premium pricing. Manufacturers that publish robust, indication-specific outcomes will gain formulary momentum; those relying on mechanistic promises will face longer adoption cycles.
2. Material segmentation will deepen, with magnesium and polymers occupying distinct clinical lanes. Magnesium alloys will continue to expand in load-bearing fixation where rapid resorption and mechanical compatibility matter, while polymers will remain strong in applications requiring tunable degradation and softer tissue integration. The opportunity lies in matching material behavior to clinical timelines rather than treating bioabsorbable technology as a single category. Companies that articulate these lanes clearly will reduce misinterpretations and accelerate surgeon confidence.
3. Supply resilience and cost control will separate sustainable players from fragile ones. With raw material concentration and precision manufacturing requirements, the ability to manage alloy sourcing, purity, and scale consistency will increasingly influence margin stability. Expect more dual-sourcing strategies, long-term supply agreements, and internal process control investments. Pricing pressure will not disappear, but it will be offset by value demonstration and supply reliability rather than by cost competition alone.
These trends carry risk. Regulatory expectations may tighten further if post-market data reveal variability in degradation or inflammatory response. Reimbursement momentum could slow if health systems demand more localized cost evidence. Magnesium supply volatility may re-emerge, affecting planning and margins. Still, the directional signal is clear: the market is moving from novelty to execution, and the winners will be those who combine material innovation with credible evidence and dependable supply.
5. Strategic Moves for Decision Makers
For manufacturers, the priority is to build a coherent evidence-to-commercialization plan around a defined material and application strategy. That means selecting indications where degradation profiles and mechanical demands align, designing clinical studies that speak to total episode value, and securing supply pathways that can withstand raw material volatility. A narrow, well-supported indication can outperform a broad but thinly evidenced portfolio in both adoption speed and pricing power.
For investors, the most durable opportunities are likely in companies that pair regulatory traction with repeatable manufacturing and a clear value narrative. Look for credible biocompatibility data, evidence of mechanical equivalence across degradation timelines, and signs that premium pricing is being justified by reduced revision, removal, or rehabilitation burden. Diversified platforms with resorbable lines integrated into established surgical franchises may offer broader exposure, while focused specialists can deliver higher optionality if they secure and defend key regulatory and clinical positions.
For procurement and clinical leaders, the practical step is to structure evaluation criteria that compare total cost of care rather than unit price alone. Pilot programs should track revision rates, removal procedures, patient-reported outcomes, and downstream resource use, not just implant performance at the time of surgery. Where evidence supports it, bioabsorbable options can reduce long-term burden in appropriate indications, but that conclusion must be validated within local clinical pathways and reimbursement realities.
The market is moving quickly enough that portfolio decisions, partnership choices, and procurement frameworks need current, granular intelligence. A detailed report can map segment-level dynamics, company-by-company regulatory status, material cost structures, and application-specific adoption signals with the granularity needed for timing and prioritization decisions.
For detailed analysis of this topic, please visit the official page: Degradable Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
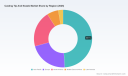
Strategic Trends and Commercial Opportunities in the Global Casting Tip and Nozzle Market
Market Overview and Core Challenges
The worldwide market for casting tips and nozzles has steadily matured into a critical enabler of modern metallurgical production. Valued at approximately $336.1 million in 2025, the market has expanded from $258.4 million in 2020, reflecting a compound annual growth rate of 5.24 percent through the early stages of the current decade. Looking ahead to 2032, the trajectory points toward roughly $480.9 million, a shift that underscores sustained demand for precision flow control and thermal management components across continuous and semi-continuous casting environments. While the growth rate is moderate rather than explosive, the underlying drivers point to meaningful structural upgrades rather than cyclical expansions. Manufacturers and foundries alike are moving beyond basic replacement parts toward engineered solutions that extend campaign lengths, reduce breakout incidents, and improve strand surface integrity.
Several converging challenges are testing the industry's adaptability. First, thermal and erosion resistance remain persistent bottlenecks. Casting environments expose tips and nozzles to extreme temperature gradients, chemical interactions with molten metal, and mechanical stress during insertion and withdrawal. When components fail prematurely, campaign interruptions, metal losses, and unplanned maintenance cascade through production schedules. Second, the supply base is navigating raw material volatility and processing constraints. High-performance refractories and ceramic composites depend on tightly controlled calcination, particle sizing, and forming methods, and any disruption in precursor availability or energy costs can compress margins or delay qualification cycles. Third, end-users are demanding more predictable performance without sacrificing flexibility. Facilities running multiple alloys, varying pour rates, or transitioning between aluminum and steel lines expect components that deliver consistent flow characteristics while accommodating frequent changeovers. Overcoming these pressures requires more than incremental material upgrades; it calls for integrated design thinking that aligns nozzle geometry, thermal profiles, and installation practices with real-world operating conditions.
The broader implication is that the market is transitioning from a commodity mindset toward engineered performance. Buyers increasingly evaluate total cost over the casting cycle rather than unit price alone, and suppliers that can demonstrate reliability, repeatability, and shorter changeover times are gaining preference. Simultaneously, the competitive field remains moderately fragmented, with market concentration reflecting a mix of specialized manufacturers and broader industrial players. This structure creates both opportunities for differentiation and risks of margin pressure where products become interchangeable. Companies that can translate material science, application expertise, and field support into measurable operational gains will be best positioned to capture value as buyers prioritize consistency and uptime over lowest upfront cost.
Key Drivers Shaping the Market
Technological innovation is one of the most visible forces reshaping the casting tip and nozzle landscape. Advances in ceramic fiber and aluminum silicate composite formulations have improved high-temperature stability, non-stick behavior, and dimensional consistency, which directly benefits aluminum casting operations where adhesion and thermal shock are persistent concerns. In steel continuous casting, zirconia-based tundish metering nozzles and precision inserts are increasingly relied upon for erosion resistance and controlled discharge, helping maintain stable flow during extended campaigns. Beyond materials, design refinement is accelerating. Nozzle and tip geometries are being optimized to deliver more uniform metal distribution, reduce turbulence, and support consistent solidification behavior. For secondary cooling in continuous casting, improvements in spray pattern uniformity and droplet control are helping producers manage strand temperatures more precisely, which can reduce surface defects and support higher throughput.
Regulatory and operational standards also play a meaningful role in shaping demand. Foundries and casting facilities operate under increasingly stringent expectations for safety, environmental compliance, and process control. While the component itself may not always be the direct subject of regulation, the operational requirements that stem from quality assurance, emissions management, and process reliability indirectly drive preference for products that reduce variability. In steel casting, for example, the need to prevent surface cracks and other strand defects through controlled secondary cooling encourages adoption of nozzles that deliver repeatable spray profiles. In aluminum operations, components that minimize contact-related sticking and support cleaner breakouts can help facilities reduce downtime and rework. These conditions reward suppliers whose products contribute to process stability and help buyers document consistent performance.
Fire Nozzle Market
Demand-side dynamics are shifting as metal producers balance quality, efficiency, and flexibility. Aluminum casting continues to represent the largest application context within this market, reflecting widespread use in high-volume production where controlled flow and thermal management are central to yield and surface quality. Steel casting remains another major pillar, with needs concentrated around tundish metering, ladle-to-tundish flow control, and secondary cooling. A growing emphasis on non-ferrous alloy casting is also expanding the scope of component requirements, as producers work with materials that can impose different thermal and chemical stresses. On the behavioral side, buyers are increasingly aligning procurement with operational outcomes: reduced air and water consumption in cooling systems, longer service life between changeouts, and greater campaign predictability. These priorities favor solutions that combine material reliability with practical usability, especially when they help plants maintain quality while managing throughput.
Supply chain and cost structure dynamics further influence competitive positioning. Producers of advanced refractories and ceramic components face the dual challenge of maintaining material consistency while managing energy-intensive processing steps and input costs. Where suppliers can streamline fabrication, stabilize batch-to-batch performance, and reduce installation complexity, they create tangible value beyond the component itself. At the same time, recent product updates from leading manufacturers indicate a clear emphasis on practical performance attributes such as zero shrinkage at high temperatures, suitability for twin-roll continuous casting, and enhanced non-stick properties for aluminum processing. These developments illustrate how commercial priorities are converging around reliability, ease of integration, and readiness for varied mill configurations. As a result, competitive advantage is increasingly determined by how well a supplier can deliver not just a part, but a solution that fits the operating environment and reduces total friction across the casting cycle.
Competitive Landscape and Leading Strategies
The market features a diverse set of players spanning specialty refractory producers, precision nozzle manufacturers, and companies with deep application focus in either aluminum or steel casting. Several firms have established strong positions by aligning product design with specific process pain points. In aluminum casting, suppliers offering complete tip assemblies designed for rapid insertion and reduced assembly effort are appealing to casthouse operators seeking to minimize setup time and variability during changeovers. In aluminum sheet, foil, and strip production using twin-roll continuous casting, companies emphasizing non-stick behavior and dimensional stability at elevated temperatures are catering to the need for consistent strip quality and reduced contact-related issues. For steel continuous casting, the most differentiated players tend to focus on flow control and secondary cooling precision, where nozzle design and spray uniformity directly influence strand quality and process productivity.
Strategic positioning among leading companies often revolves around three reinforcing advantages: material performance, application engineering, and service reliability. Material performance is foundational; zirconia-based metering nozzles and high-temperature ceramic inserts are commonly associated with erosion resistance and extended campaign life in steel casting, while aluminum silicate and ceramic fiber composites are valued where non-stick behavior and high-temperature stability matter. Application engineering is equally important because casting conditions vary widely by alloy, temperature, pour rate, and equipment geometry. Suppliers that provide interchangeable configurations, predefined installation practices, and guidance on flow control can reduce trial-and-error for buyers and improve repeatability across shifts. Service reliability completes the picture: timely availability of replacement components, predictable lead times, and technical support during qualification and troubleshooting help maintain campaign continuity, which is often more important to buyers than minor price differences.
Recent market developments reinforce the shift toward performance-led differentiation. Updates in aluminum casting nozzle and tip offerings have highlighted high-temperature calcination, non-stick characteristics, and suitability for twin-roll casting environments, reflecting an emphasis on operational consistency and reduced sticking. In steel casting, continued attention to tundish metering, ladle-to-tundish flow control, and secondary cooling spray patterns signals that precision and process stability remain central concerns. These moves suggest that companies are competing less on generic part availability and more on targeted problem solving.
The competitive landscape is evolving along multiple axes. Consolidation is plausible where scale in manufacturing, distribution, or application support can lower cost and broaden portfolio breadth, particularly for suppliers able to serve both aluminum and steel environments. At the same time, fragmentation persists because specific alloy systems, nozzle geometries, and mill configurations create room for specialized players with deep process knowledge. New entrants can still find opportunities by focusing on underserved niches, such as customized metering solutions, improved cooling spray patterns, or components designed for faster changeover in multi-alloy operations. The overall direction points toward greater segmentation by application needs and material requirements, with winners likely to be those that combine material robustness with practical usability and dependable support.
Jet Engine Nozzles Market
Future Trends and Commercial Implications
Over the next three to five years, one of the clearest trends will be continued prioritization of reliability and extended campaign performance. As metal producers face pressure to maintain quality while optimizing throughput, components that resist erosion, reduce sticking, and deliver consistent flow will gain preference. This trend favors suppliers that can demonstrate measurable improvements in service life, fewer unplanned interruptions, and stable performance across varying operating conditions. Commercially, this creates opportunities for products backed by strong field data and clear application guidance, especially when buyers can tie component performance to reduced downtime or improved yield.
A second trend will be increased attention to precision in cooling and flow control. In continuous steel casting, uniform spray patterns and controlled secondary cooling are likely to remain central to surface quality and productivity goals. In aluminum operations, the focus will likely stay on reducing contact issues and supporting smooth metal delivery across twin-roll and related casting configurations. As a result, there is commercial potential in solutions that improve process repeatability while helping facilities manage water and air usage more efficiently. Suppliers that can align nozzle design with real-world cooling and discharge requirements will be well placed to capture interest from operators seeking both quality and resource efficiency.
A third trend is the gradual move toward more integrated procurement and qualification approaches. Buyers are increasingly evaluating parts in the context of broader process goals, including changeover speed, installation consistency, and support during commissioning or troubleshooting. This creates room for differentiated offerings that reduce assembly complexity, standardize fit-up, and simplify supplier coordination across multiple casting lines. However, uncertainty remains. Raw material costs, energy intensity of high-temperature processing, and the pace of equipment upgrades in end-user facilities can influence adoption timing and margin resilience. Shifts in alloy demand, changes in domestic production philosophy, or supply interruptions can also alter purchasing patterns. Companies that build flexibility into product lines and maintain reliable supply and technical support will be better equipped to navigate these variables.
Actionable Guidance for Decision Makers
For manufacturers and producers, the priority should be to evaluate casting tips and nozzles based on total process impact rather than unit price alone. That means considering service life, installation time, flow consistency, cooling performance, and support during changeovers. Where multiple alloys or casting configurations are in use, standardizing on components that balance flexibility with predictable performance can reduce variability and simplify maintenance planning. It is equally important to align procurement with operational objectives such as surface quality, campaign continuity, and resource efficiency, then validate component choices through controlled trials that reflect actual plant conditions.
For investors, the market offers exposure to steady, demand-backed growth in enabling casting components, but differentiation will matter more than broad participation. The most compelling opportunities are likely to be found in suppliers with strong material capability, clear application focus, and the ability to reduce total friction for end-users. Evaluating track records in qualification support, supply reliability, and portfolio breadth across aluminum and steel environments can help identify businesses positioned to capture value as buyers prioritize consistency and uptime. Monitoring product updates that emphasize high-temperature stability, non-stick behavior, and precision cooling can also provide early signals of where commercial emphasis is heading.
PW Consulting
For procurement and sourcing teams, the most effective strategy is to structure evaluations around performance criteria that reflect the operating environment. This includes requesting application-specific data, comparing installation and changeover requirements, and clarifying lead times and support arrangements before committing to larger volumes. Where possible, coordinate with process engineers to ensure that component selection supports downstream goals such as strand quality, cooling uniformity, and campaign predictability. For organizations seeking a fuller picture of segment dynamics, regional patterns, and supplier-specific positioning, the complete research report provides more detailed breakdowns and tailored recommendations to support procurement planning and strategic review.
For detailed analysis of this topic, please visit the official page: Worldwide Casting Tip And Nozzle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Worldwide Non-invasive Ventilation Masks Market
Market Overview: Navigating a Transforming Respiratory Care Landscape
The global non-invasive ventilation (NIV) masks market is experiencing a period of sustained expansion, driven by evolving respiratory care needs and a shifting clinical paradigm toward less invasive treatment modalities. Market valuation has grown steadily from 2020 through 2025, reflecting consistent demand across healthcare settings. The trajectory from 2026 to 2032 indicates continued appreciation, supported by expanding indications, aging demographics, and technological refinement. A compound annual growth rate of 6.21 percent positions the category as a resilient segment within the broader respiratory devices ecosystem, with revenue measured in millions of U.S. dollars.
Revenue distribution reveals that North America continues to represent the largest regional share, followed by Europe and Asia Pacific. The Americas benefit from mature reimbursement frameworks, high adoption of home-based respiratory therapies, and a well-established hospital procurement infrastructure. Europe maintains a strong foothold through structured clinical guidelines and broad access to non-invasive ventilation in both acute and chronic care pathways. Asia Pacific is increasingly contributing to growth momentum as healthcare systems scale capacity, respiratory disease prevalence rises, and access to advanced ventilation technologies improves across urban and semi-urban facilities. Latin America and the Middle East and Africa, while smaller in absolute terms, are developing markets where infrastructure investments and disease burden are gradually expanding the addressable patient base.
On the product side, full-face masks lead in revenue contribution, reflecting their broad application in acute and chronic non-invasive ventilation scenarios where secure sealing and high-pressure tolerance are essential. Nasal masks form a substantial second category, favored for patient comfort and suitability in longer-duration therapy. Nasal pillow masks and total face masks represent smaller but strategically important sub-segments, each addressing distinct clinical workflows and patient preferences. From an end-user perspective, hospitals and clinics remain the dominant application environment, driven by acute care demand and institutional procurement cycles. Home healthcare constitutes a significant and growing share, underscoring the shift toward decentralized respiratory management. Ambulatory care centers represent a more niche but expanding channel, particularly in settings that emphasize outpatient respiratory support and early discharge pathways.
Sleep Apnea Masks Market
Market structure is moderately concentrated, with a small group of leading manufacturers capturing a majority of revenue. This concentration reflects the technical barriers associated with mask design, sealing performance, material quality, and regulatory clearance requirements. At the same time, the presence of specialized and regional players indicates an industry in which differentiation through ergonomics, patient comfort, and clinical-specific configurations remains viable. Several key challenges are shaping the current market inflection point. First, product fit and patient adherence continue to be persistent clinical concerns; even advanced mask designs must contend with variability in facial anatomy, pressure tolerance, and prolonged wear comfort. Second, the balance between single-use clinical efficiency and cost containment is becoming more pronounced, particularly as hospitals evaluate total cost of care rather than unit price alone. Third, regulatory pathways and reimbursement frameworks are evolving in ways that influence both product development priorities and market access timing, especially in the United States where coverage criteria and device classification directly affect adoption velocity.
For executives and investors, the core implication is that the market is expanding, but growth is not uniformly distributed across products, channels, or regions. Competitive success depends on aligning design, clinical evidence, and access strategy with the environments where non-invasive ventilation is most actively deployed.
PW Consulting
Key Growth Drivers: Technology, Policy, Demand, and Supply Chain Dynamics
Several interconnected forces are accelerating the expansion of the NIV masks market. The first and most visible is technological innovation in mask design and interface engineering. Manufacturers are increasingly focusing on cushion materials, seal stability under varying pressure conditions, and headgear architectures that reduce pressure points while preserving therapeutic effectiveness. Medical-grade silicone remains a common interface material because of its flexibility, hypoallergenic profile, and ability to conform to facial contours for effective sealing. This material foundation supports ongoing refinement rather than radical substitution, enabling manufacturers to iterate on comfort and performance without compromising clinical reliability. Recent product introductions illustrate this trajectory, including mask portfolios that span nasal, full-face, and specialized configurations, with interchangeable components designed to adapt to different therapy setups. Such modularity is particularly relevant in hospital environments, where clinicians value flexibility across patient types and ventilation modes.
A second driver is the evolving policy and regulatory environment. In the United States, NIV masks are classified as Class II devices under 21 CFR 868.5895 and require 510(k) clearance for marketing as accessories for non-invasive ventilation. This regulatory structure creates a defined pathway for market entry, but it also places a premium on timely clearance, clinical differentiation, and documentation of intended use. Recent regulatory activity underscores how actively the competitive field is moving. Clearances have been obtained for hospital-focused vented and non-vented mask ranges, as well as for families of NIV masks intended for single-patient use in the hospital environment. These approvals matter because they expand the set of commercially available options and can shift procurement decisions by giving clinicians more choices in fit, circuit compatibility, and infection-control preferences. Regulatory momentum also signals to the market that non-invasive ventilation interfaces remain a priority category for device innovation and review.
The third driver lies on the demand side, where clinical practice and care-setting trends are reshaping adoption. There is a continuing shift toward earlier and broader use of non-invasive ventilation in both acute and chronic respiratory failure management, particularly when clinicians seek to avoid intubation or support patients outside the intensive care unit. At the same time, home-based respiratory care is becoming more central to long-term management strategies. CMS updated the National Coverage Determination for non-invasive positive pressure ventilation in the home for chronic respiratory failure consequent to COPD, expanding coverage for respiratory assist devices and home mechanical ventilators with revised criteria. Notably, the updated framework no longer requires overnight oximetry in certain cases and uses clinical thresholds such as PaCO2 ≥ 52 mmHg or documentation that sleep apnea is not the predominant cause. This kind of reimbursement evolution can broaden the eligible patient population and strengthen the economic case for home-based non-invasive therapy, indirectly supporting demand for appropriate masks and interfaces over time.
Non-invasive Ventilation Masks Market
A fourth driver is the changing supply chain and cost structure environment. Healthcare providers are increasingly attentive not only to device performance but also to the downstream economics of therapy, including consumables, staffing burden, and infection-control workflows. This has increased interest in products that can simplify setup, improve seal consistency, and reduce remasking or adjustment time. For manufacturers, cost pressures are encouraging disciplined material selection, manufacturing efficiency, and design choices that balance performance with scalability. The market is also seeing interest in products tailored to pediatric and infant care, where specialized sizing and comfort features can address a distinct clinical need and create opportunities for differentiation. Newer catalog additions targeting infants and children highlight how comfort-oriented engineering, swivel elbow designs, and adjustable fitting mechanisms are being used to meet the requirements of smaller patient populations.
Taken together, these drivers suggest that the NIV masks market is being shaped less by a single breakthrough and more by cumulative improvement across materials, regulatory readiness, reimbursement alignment, and clinical workflow. Companies that can integrate these elements into coherent product and access strategies are better positioned to convert clinical need into durable commercial traction.
Competitive Landscape: Positioning, Differentiation, and Evolving Market Structure
The competitive environment in the NIV masks market is defined by a combination of established multinational manufacturers and specialized players with strong clinical or regional focus. ResMed maintains a prominent position through hospital non-vented full-face NIV masks designed for single-use, with product options engineered to seal effectively under high pressures up to 40 cm H2O. This emphasis on high-pressure performance and single-use design aligns with acute-care requirements where seal reliability and infection-control considerations are paramount. Fisher & Paykel Healthcare offers a broad portfolio that includes full-face masks with vented and non-vented configurations in multiple sizes, as well as under-nose, bridge-free designs compatible with single-limb circuits. Its recent FDA 510(k) clearance for a hospital vented full-face mask range illustrates a strategy centered on expanding clinically relevant options and strengthening compatibility with common ventilation circuits. Philips Respironics contributes oro-nasal and face mask solutions with headgear and cushion designs intended for hospital-based non-invasive ventilation, reinforcing its presence in institutional care settings. Hamilton Medical has expanded its mask portfolio across nasal, full-face, and specialized configurations with interchangeable elbows and multiple sizes for adult and pediatric patients, reflecting a product architecture built around adaptability across therapy options.
Beyond these larger platforms, a second tier of competitors brings distinct value propositions. Dräger emphasizes customizable NIV masks as part of complete non-invasive ventilation solutions for acute care, with a focus on seal and fit to support gentle and cost-effective therapy. Dimar S.p.A. manufactures families of NIV masks for single-patient use in hospital environments, positioning itself as a provider of patient-interface accessories within broader ventilation workflows. GaleMed focuses on premium NIV CPAP masks designed for comfort and therapy performance, while Hans Rudolph has reimagined full-face masks with an emphasis on fit and care without sacrificing treatment effectiveness. DEAS supplies an extensive portfolio across anesthesia, ventilation, and non-invasive ventilation needs, and AirLife offers lightweight silicone full-face and nasal masks in vented and non-vented options across multiple sizes, underscoring clinician reliability and patient comfort. These companies illustrate that even within a concentrated market, there is meaningful differentiation in design philosophy, target setting, and end-user value proposition.
The strategic positioning of leading players tends to converge around a few priorities. The first is clinical fit and sealing performance, especially under high pressure or during extended use. The second is compatibility with different circuit types and hospital workflows, including vented versus non-vented configurations and single-limb circuit use. The third is patient comfort and ease of fitting, which affects adherence and reduces clinical adjustment time. A fourth priority is regulatory readiness and documentation, which has become increasingly important as procurement teams evaluate both clinical performance and compliance certainty. Companies that can combine these attributes with a clear intended-use narrative often gain an advantage in acute-care formulary decisions and, increasingly, in home-care and ambulatory channels where ease of use matters.
Market structure is evolving along several axes. Consolidation remains a possibility as larger platforms seek to strengthen respiratory portfolios and smaller players look for partnership or distribution pathways that broaden reach. At the same time, differentiation is intensifying rather than narrowing, because mask design is highly application-specific. A configuration that performs well in acute hospital ventilation may not be ideal for chronic home use, and vice versa. This creates room for specialized entrants that target particular patient populations, care settings, or clinical workflows. The presence of recent product launches and regulatory clearances across multiple companies suggests an industry in motion, with competitors actively expanding portfolios to address gaps in sizing, circuit compatibility, and comfort. Newer entries and catalog expansions in pediatric and infant segments further indicate that incumbents are not only competing on scale but also on clinical specificity.
For buyers and investors, the practical implication is that the market is not a simple hierarchy of incumbents and followers. It is a landscape in which leadership is contested through product architecture, regulatory timing, and alignment with the care settings where non-invasive ventilation is most actively adopted. Strategic advantage will likely accrue to those who can demonstrate consistent performance across the environments that matter most to their customers.
Future Outlook: Trajectories, Opportunities, and Watchpoints
Over the next three to five years, the NIV masks market is likely to be shaped by a small number of high-impact trends. The first is the continued expansion of home-based and ambulatory non-invasive ventilation, supported by evolving reimbursement frameworks and a broader shift toward managing chronic respiratory conditions outside the hospital. If coverage pathways remain favorable and clinical confidence in home NIPPV grows, demand for masks suited to long-term wear, ease of fitting, and patient convenience could increasingly influence product mix and procurement patterns. This creates an opportunity for manufacturers that can bridge acute-care performance with home-care usability, especially where patient adherence is a decisive clinical factor.
The second trend is the growth of application-specific and population-specific mask designs. The market is already seeing movement toward more modular portfolios, pediatric and infant configurations, and masks optimized for particular circuit types and therapy modes. As clinical protocols continue to differentiate between acute ventilation, chronic management, and transitional care, products that are purpose-built for these contexts may gain preference over generalized offerings. This trend favors companies that invest in fitting systems, sizing breadth, and design features that reduce mask adjustment and improve comfort across varied patient anatomies.
The third trend is the increasing importance of regulatory timing and evidence-driven differentiation. Because NIV masks are Class II devices requiring 510(k) clearance in the U.S., and because hospital procurement teams increasingly weigh compliance certainty alongside performance, the speed and clarity of regulatory approval can be a meaningful commercial factor. Companies that align product development with reimbursement and clinical evidence needs may be better positioned to capture adoption in high-value settings. At the same time, cost containment pressures will likely remain a persistent watchpoint; providers may favor solutions that reduce remasking, simplify infection-control workflows, and support predictable consumable spending.
These trends carry both opportunity and uncertainty. On the opportunity side, the combination of broader home-care use, more targeted product designs, and active regulatory activity points to a market in which well-positioned portfolios can gain share without relying solely on price competition. On the risk side, market growth may be uneven if reimbursement policies change, if clinical guidelines shift the balance between non-invasive and invasive approaches, or if supply chain and material costs alter margin expectations. Additionally, patient adherence challenges and the inherent variability of facial anatomy mean that even strong product designs must continue to earn confidence through real-world performance. The companies most likely to navigate this environment successfully will be those that treat mask design not as an isolated accessory category, but as an integral part of the broader non-invasive ventilation pathway.
Strategic Implications: What Decision-Makers Should Do Next
For manufacturers, the immediate priority is to align product roadmaps with the care settings and patient populations generating the strongest demand. This means investing in seal stability, comfort, and modular compatibility for hospital use while also ensuring that home-care and ambulatory offerings address adherence and ease of fitting. Regulatory planning should be treated as a strategic lever rather than a compliance checkbox, particularly given the active clearance environment and the commercial value of timely market access. Companies should also consider where portfolio breadth adds real clinical value versus where it simply increases complexity, because buyers are likely to reward designs that simplify selection and reduce workflow friction.
For investors, the key question is not whether the category will grow, but which segments and strategies will convert growth into durable margin and share gains. Preference may be given to players with differentiated product architecture, clear regulatory momentum, and strong alignment with reimbursement trends in home and hospital care. Particular attention should be paid to companies that can demonstrate value beyond unit price, including reductions in clinical adjustment time, improved adherence, and compatibility with evolving ventilation circuits. Portfolio exposure to pediatric, infant, and specialized acute-care configurations may offer additional optionality, especially if these segments continue to expand in clinical relevance.
For procurement and clinical decision-makers, the practical aim is to evaluate masks not only on immediate specifications but also on total therapy performance. This includes assessing seal reliability under anticipated pressure ranges, compatibility with existing circuits and workflows, sizing flexibility for diverse patient populations, and the evidence or clearance status that supports confident formulary inclusion. Given the pace of product introductions and regulatory updates, ongoing market intelligence can help procurement teams avoid delays in adoption and ensure that purchasing decisions reflect the latest clinically relevant options and access conditions.
As the market evolves, the winners will be those who connect product design, regulatory readiness, reimbursement awareness, and real-world usability into a coherent strategy. Detailed segment-level data, competitive benchmarks, and tailored scenario analysis can help organizations move from general market awareness to specific, executable decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Non-invasive Ventilation (NIV) Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Biliary Catheters Market: Why 5.48% CAGR Signals a Strategic Shift by 2032
By pmarketresearch, 2026-09-18
Globular Trends in the Worldwide Biliary Catheters Market: Strategic Opportunities for Industry Leaders
Market Overview: Scale, Trajectory, and Critical Challenges
The global biliary catheters market has entered a phase of sustained expansion, driven by an evolving interventional gastroenterology landscape and growing demand for minimally invasive biliary drainage solutions. Valued at approximately $645.5 million in the base year of 2025, the market has demonstrated consistent growth from $503.18 million in 2020. This trajectory reflects a compound annual growth rate of 5.48 percent over the forecast period extending through 2032, with projected revenues approaching $937.75 million by the end of the forecast horizon. Such figures underscore a market that is not merely expanding in absolute terms but maturing in complexity, as clinical protocols, reimbursement frameworks, and product engineering converge to shape procurement and adoption decisions.
PW Consulting
The geographic distribution of demand reveals a market where North America and Europe continue to anchor the largest revenue shares, supported by established endoscopy infrastructure, high procedural volumes, and mature reimbursement pathways. Asia Pacific represents a rapidly intensifying region, where rising healthcare expenditure, expanding specialty clinic networks, and growing adoption of percutaneous biliary interventions are accelerating volume growth. Latin America and the Middle East and Africa contribute smaller but strategically relevant portions of the market, often characterized by procurement cycles tied to public health initiatives and regional capacity-building programs. Across these regions, the product mix leans heavily toward external drainage catheters, which maintain the largest share by type, followed by internal drainage catheters and conversion catheters that serve more specialized clinical pathways. Hospitals remain the dominant end-user segment, reflecting the central role of inpatient interventional suites and radiology departments in biliary drainage procedures, while specialty clinics and ambulatory surgical centers represent growing channels for routine and follow-up interventions.
Despite the favorable growth trajectory, the market faces a set of structural challenges that will define competitive dynamics over the coming years. First, the regulatory classification of biliary catheters and accessories under Class II special controls introduces a persistent compliance burden. Manufacturers must navigate clearance pathways that demand rigorous demonstration of safety, performance, and intended use, particularly when introducing design modifications or new material formulations. Second, reimbursement architecture exerts significant influence on adoption patterns. Procedural coding for catheter placement, exchange, and imaging guidance creates a billing environment where clinical utility must be paired with clear documentation and coding accuracy. Any shifts in coverage policy, coding interpretation, or hospital cost pressure can rapidly alter procurement behavior. Third, the market exhibits meaningful concentration, with the top three competitors accounting for over forty percent of revenue and the top five exceeding fifty-eight percent. This concentration signals both the presence of established incumbents with strong distribution relationships and the potential for consolidation, as smaller manufacturers seek scale or partnerships to compete effectively. Together, these factors create a market where growth is available, but capturing it requires disciplined execution across regulatory, clinical, and commercial dimensions.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Dynamics
The expansion of the biliary catheters market is propelled by a convergence of clinical, technical, and systemic forces. At the forefront is technological innovation in catheter design and delivery systems. Manufacturers are increasingly differentiating products through features such as locking loop mechanisms, radiopaque markers, hydrophilic coatings, and enlarged drainage apertures. These enhancements address practical clinical needs: improved positional stability during prolonged drainage, clearer fluoroscopic visibility during placement, reduced friction during insertion, and higher drainage efficiency for complex strictures or obstructed ducts. The availability of multiple configurations, including large-hole drainage catheters and hydrophilic-coated variants, reflects an industry response to the diversity of biliary anatomy and procedural contexts. In parallel, the use of nitinol reinforcement in select drainage catheters illustrates a focus on kink resistance and structural durability, attributes that reduce complications and improve reliability in long-term or tortuous drainage pathways.
Worldwide Pancreatic and Biliary Stent Market
Regulatory and reimbursement dynamics form a second critical driver. Biliary catheters and accessories are classified as Class II devices under special controls, a framework that balances access with oversight by requiring submission of performance data and adherence to recognized standards. Recent regulatory clearances illustrate how incremental innovation can still unlock market entry. For example, a wireguided balloon dilation catheter for biliary applications recently received FDA 510(k) clearance under a classification covering stents, drains, and dilators for biliary ducts, signaling continued openness to devices that bridge dilation and drainage workflows. Similarly, a biodegradable pancreatic stent gained clearance under the biliary catheter and accessories regulation, highlighting how adjacent product categories can leverage existing regulatory pathways to introduce materials and designs that may influence future biliary drainage strategies. On the reimbursement side, procedural codes governing percutaneous biliary drainage, exchange, and imaging guidance create a structured but scrutinized economic environment. Hospitals and clinics evaluate catheter choices not only on clinical performance but also on coding efficiency, documentation burden, and total cost of care, making reimbursement alignment a decisive factor in purchasing decisions.
Demand-side changes represent a third driver. The procedural volume for biliary drainage is expanding as interventional endoscopy and interventional radiology continue to gain traction for managing obstructions, strictures, leaks, and post-surgical complications. Clinicians increasingly favor percutaneous and endoscopic approaches that minimize invasiveness, reduce recovery time, and support outpatient or short-stay pathways where feasible. This shift is amplified by staffing and capacity constraints in many healthcare systems, which incentivize solutions that streamline procedures, reduce complication rates, and support repeat interventions without compromising outcomes. The growth of specialty clinics and ambulatory surgical centers as procurement channels reflects this trend, as these settings seek durable, user-friendly devices that fit high-throughput workflows and support standardized protocols.
Supply chain and cost structure considerations round out the driver set. The market includes a mix of large multinational manufacturers and specialized regional producers, creating a competitive ecosystem where scale, sourcing reliability, and manufacturing precision all matter. Material selection, coating consistency, and dimensional tolerances influence both performance and cost, while regional manufacturing footprints can affect lead times, logistics resilience, and pricing flexibility. In an environment where hospitals are sensitive to total cost and supply continuity, suppliers capable of delivering dependable quality, clear technical support, and responsive service gain a measurable advantage. The presence of regional manufacturers in markets such as India and Taiwan also indicates an ongoing diversification of supply sources, which can introduce cost-competitive alternatives and expand availability in emerging procurement contexts.
Competitive Landscape: Strategic Positioning and Market Evolution
The competitive field in biliary catheters is shaped by a combination of established device manufacturers and focused specialists, each pursuing distinct strategic advantages. Leading participants emphasize product portfolios that span multiple catheter types, procedural techniques, and delivery approaches. Some suppliers have built reputations around locking loop options and radiopaque markers designed for percutaneous biliary drainage, aiming to reduce migration risk and improve procedural visibility. Others differentiate through multipurpose styles compatible with direct stick or Seldinger techniques, providing clinicians with flexibility across varied access scenarios. A further set of players highlights large drainage apertures and hydrophilic coatings, positioning their devices around drainage efficiency and ease of insertion. This diversity of design philosophy indicates a market where clinical differentiation remains viable, but only when paired with robust evidence, reliable supply, and strong service support.
Strategic positioning among incumbents often revolves around three pillars: portfolio breadth, procedural alignment, and integration with procedural kits. Portfolios that cover external, internal, and conversion catheters allow suppliers to address a wider range of clinical indications and maintain relationships across multiple procedure types. Procedural alignment appears in designs that accommodate common access techniques and in the availability of kits that bundle catheters with necessary accessories, simplifying procurement and standardizing setup. Integration with broader interventional portfolios is also notable, as some manufacturers embed biliary catheters within larger drainage and interventional product lines, leveraging cross-selling and clinical familiarity to reinforce market presence. These approaches help incumbents defend share in a concentrated market while creating barriers for new entrants that lack equivalent clinical relationships or procedural coverage.
The market is evolving along several trajectories. Consolidation pressure persists given the revenue concentration among leading firms, which may encourage acquisitions, partnerships, or licensing arrangements as smaller manufacturers seek scale and broader distribution. At the same time, differentiation is increasing in the opposite direction, as specialized designs and material innovations create niches for focused players who can deliver distinct clinical value. New entrants and regional manufacturers add further complexity by introducing cost-competitive options and expanding supply diversity, particularly in growth regions where local support and affordability influence purchasing. Regulatory developments will continue to shape this evolution: clearances that validate new designs or materials can open doors for innovators, while the Class II special controls framework ensures that all participants maintain a baseline of demonstrated safety and performance. Meanwhile, reimbursement dynamics will act as a constant filter, rewarding devices that support efficient coding, clear documentation, and predictable procedural workflows. The net effect is a landscape where scale and relationships matter, but precise clinical utility and adaptable commercial models increasingly determine who gains share.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Looking ahead, the biliary catheters market is likely to be shaped by three interrelated trends. The first is continued product refinement oriented toward procedural efficiency and complication reduction. Expect broader adoption of catheters with enhanced drainage area, improved visibility features, and coatings or reinforcements that reduce friction and kinking. As clinicians accumulate experience with these design improvements, procurement patterns may favor devices that demonstrably support faster setup, more reliable positioning, and fewer exchanges, especially in high-volume settings where time and outcomes directly affect throughput and cost.
The second trend is the growing importance of procedural ecosystem alignment. Devices will increasingly be evaluated not in isolation but as part of integrated workflows that include access technique, imaging guidance, coding efficiency, and post-procedure management. Suppliers that provide clear guidance on coding relevance, procedural setup, and exchange protocols may gain an edge, particularly as hospitals seek to reduce administrative friction and standardize care pathways. This trend creates opportunities for manufacturers that invest in clinician education, procedural support materials, and documentation-friendly product information.
Medical Catheters Market
The third trend is regional expansion coupled with supply chain diversification. Growth in Asia Pacific and other emerging procurement regions will likely accelerate as infrastructure improves and procedural volumes rise. At the same time, the presence of regional manufacturers and varied sourcing options may increase price competition and broaden availability. This dynamic presents both opportunity and risk: it can expand addressable volume and create partnerships for global suppliers, but it can also pressure margins and require careful quality assurance and service planning. Uncertainty remains around the pace of reimbursement evolution, the stringency of regulatory review for design changes, and potential shifts in procurement budgets as healthcare systems balance cost control with procedural demand. Companies that monitor these signals closely and align product strategy with local clinical and economic realities will be better positioned to convert growth into sustainable share.
Strategic Actions for Decision Makers
For manufacturers, the priority is to sharpen clinical differentiation while reinforcing commercial reliability. Invest in design features that address measurable procedural needs, and support those features with clear documentation, compatible procedural kits, and responsive technical service. Ensure that regulatory and reimbursement considerations are embedded in product planning from the outset, so that new designs are not only technically sound but also aligned with coding and procurement realities. Building relationships with high-volume centers and specialty clinics can help validate performance in real workflows and strengthen adoption over time.
For investors, the market rewards disciplined capital allocation toward companies with defensible clinical positioning, stable supply operations, and scalable commercial infrastructure. Evaluate not only product portfolios but also the strength of procedural support, the consistency of regulatory execution, and the ability to navigate reimbursement frameworks. Opportunities may arise through targeted partnerships, acquisitions of niche technologies, or investments in regional manufacturing capability that improves supply resilience and market access. Attention to concentration dynamics is important, as consolidation could reshape competitive positions and create both risks and openings.
For procurement leaders and clinical decision makers, the focus should be on total value rather than unit price alone. Assess catheters based on drainage performance, insertion reliability, compatibility with existing access techniques, and support for efficient documentation and coding. Standardizing where appropriate can reduce variation and simplify training, while selective use of specialized designs can address complex cases more effectively. Engaging suppliers that provide clear procedural guidance and dependable service can help maintain throughput and reduce avoidable complications. As the market continues to evolve, access to detailed segment-level intelligence and tailored commercial insights can support more precise planning and risk management. Readers seeking deeper segmentation data, competitive benchmarking, and customized strategic guidance may consider reviewing PW Consulting’s comprehensive research report on this market.
For detailed analysis of this topic, please visit the official page: Worldwide Biliary Catheters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Probe Cards Market: Why 7.45% CAGR and Asia Pacific Dominance Redefine Growth
By pmarketresearch, 2026-09-18
Navigating the Worldwide Probe Cards Market: Strategic Trends and Commercial Opportunities (2025–2032)
The global market for probe cards entered a phase of structural expansion in 2025, with total revenue reaching approximately USD 2.94 billion. Over the historical window from 2020 through 2025, the segment demonstrated volatile but ultimately upward momentum, reflecting both cyclical semiconductor demand and the accelerating need for wafer-level test infrastructure. Looking ahead to 2032, revenue is projected to surpass USD 4.8 billion, driven by a consistent compound annual growth rate of 7.45 percent. This trajectory signals more than steady demand; it indicates a market undergoing technological maturation, geographic rebalancing, and increasing specialization tied to advanced packaging and high-performance computing workloads.
It is important to recognize the limited window between headline growth and operational reality. The market remains highly concentrated, with three firms capturing more than half of total revenue and five firms accounting for nearly three-quarters. This concentration creates both stability and fragility. Incumbent suppliers benefit from entrenched qualification cycles, long-term design-in relationships, and deep process knowledge, yet it also means that late entrants and regional players must find sharp differentiation to escape the margins of the middle market. At the same time, the customer base is fragmenting by design complexity. Foundries and logic manufacturers, memory device producers, and analog/Radio Frequency fabricated ecosystems each place different demands on probe card performance, lifespan, and interface architecture, making one-size-fits-all solutions increasingly untenable.
Within that backdrop, the industry faces several defining challenges. The first is technological transition at advanced nodes. As wafer geometries shrink and multi-die architectures become standard, probe cards must sustain finer pitch, higher pin counts, and more stable contact reliability across thousands of test cycles. The second challenge is timing, particularly the alignment between probe card availability and fab ramp schedules. Longer lead times can create bottlenecks at the most critical moment in product launches, especially when test capacity becomes a gating factor for yield maturation. The third challenge is cost pressure combined with scope expansion. Customers increasingly expect suppliers to support not only traditional wafer acceptance test but also more complex validation for 3D and 2.5D integration, high-bandwidth memory, and advanced logic stacks. Meeting these expectations requires more than incremental refinements; it demands new materials strategies, precision manufacturing, and closer co-development with device makers.
For business leaders, the immediate implication is straightforward: probe cards are no longer a commoditized consumable. They are a strategic interface between process technology and test yield, and their performance increasingly determines how quickly new nodes and new packaging formats can reach volume production. Companies that understand where the market is intensifying—and where it is splintering—will be better positioned to plan product roadmaps, secure qualified supply, and make informed capital decisions.
Key Drivers Reshaping the Probe Cards Market
Several forces are converging to shape demand, supply, and competitive positioning over the next several years. The most consequential is the pace of device architecture change. Advanced nodes, high-bandwidth memory stacks, and heterogeneous integration are pushing test interfaces to their practical limits. As design rules tighten, probe cards must deliver higher contact density, improved signal integrity, and more consistent mechanical behavior across large wafer areas. That requirement alone is accelerating adoption of micro-electro-mechanical systems-based probe cards, which can support finer pitch and higher pin counts more effectively than many legacy approaches. Vertical probe card designs are also gaining relevance because they can provide improved reliability and easier integration in certain advanced test configurations. The result is a market in which product architecture choices are being driven by test requirements that are themselves dictated by device complexity, not by probe card conventions.
Policy and regional industrial strategy form the second major driver. Semiconductor sovereignty efforts have encouraged governments to support domestic fabrication capacity, packaging ecosystems, and qualifying local suppliers. This is visible in new facility investments and regional expansion strategies that align probe card production more closely with where advanced fabs are being built. A notable example is the opening of an approximately EUR 80 million facility in Dresden aimed at supporting European semiconductor fabs, a move that reflects a broader shift toward localized supply and regional resilience. In parallel, tighter export controls and trade barriers are beginning to reshape cross-border equipment and component flows. These dynamics do not simply alter logistics; they influence which companies can serve which markets, how long qualification cycles take, and whether global suppliers must assemble regional production footprints to remain competitive.
The third driver is demand-side behavior across end-use markets. Memory remains a central application for probe cards, but the composition of memory demand is changing as high-bandwidth memory becomes tightly coupled with accelerator and AI workloads. Foundries and logic manufacturers continue to dominate revenue share, but the test requirements within that segment are diversifying rapidly. New architectures require probe card solutions that can handle more complex test patterns, higher bandwidth needs, and more demanding mechanical tolerance. At the same time, advanced packaging trends such as chiplets are changing the test conversation from single-die validation to multi-component interface validation. This broadens the scope of probe card design and encourages closer partnership between test suppliers and packaging or assembly houses.
Supply chain and cost dynamics complete the picture. Raw material constraints and geopolitical tensions have introduced meaningful variability into production planning. In recent years, lead times for probe card production have experienced delays of up to 20 percent in some cases, illustrating how fragile schedules can become when materials such as tungsten and copper are disrupted or when regional trade conditions shift. Ceramic substrates for probe cards, particularly 300mm formats, also represent a concentrated materials dependency, with a dominant share of the relevant materials market tied to those components. In response, manufacturers are increasing localized production and diversifying supply chains, reducing exposure to single-source bottlenecks. This shift has strategic implications: suppliers that can guarantee stable lead times, consistent quality, and resilient sourcing are increasingly differentiating themselves on reliability as much as on performance.
The overarching insight is that probe card demand is being shaped at the intersection of design complexity, regional policy, and supply resilience. Each of these drivers pushes the market toward higher specialization and tighter co-development, which in turn raises the value of suppliers that can move quickly, qualify early, and sustain production predictability.
Competitive Landscape and Leading Strategies
The probe cards market continues to be defined by a relatively small group of dominant suppliers supported by a broader field of specialized players. At the top tier, leading global providers of advanced wafer probe cards have built strong positions across logic, foundry, DRAM, and high-bandwidth memory applications. These companies compete not just on probe card hardware, but on the ability to sustain technology roadmaps, secure qualification with major manufacturers, and support complex test environments at scale. Their strength comes from a combination of process expertise, broad application coverage, and long-established relationships with high-volume device makers.
A second tier of major suppliers has expanded its relevance through advanced micro-electro-mechanical systems and vertical probe technologies, often targeting high-performance wafer testing for global foundries and integrated device manufacturers. Another cluster of well-established Japanese manufacturers focuses on precision probe cards for fine-pitch and advanced node testing, leveraging strong engineering heritage and close ties to Asian semiconductor ecosystems. Taiwan-based suppliers have strengthened their presence by emphasizing innovative solutions, with some expanding capacity to address AI and high-performance computing-related demand. South Korean suppliers remain important participants, especially where memory and logic testing intersect with domestic fabrication priorities. European and UK-based firms contribute specialized capabilities, including high-quality contact solutions, blade and cantilever designs, and vertical probe cards with high voltage or current capabilities. Together, these players create a market in which geography, technology focus, and application specialization all matter.
Recent developments show how companies are competing for positional advantage. One major supplier strengthened its micro-electro-mechanical systems position by acquiring a California-based firm, adding patents tied to vertical spring optimization for probe cards. That kind of move illustrates a broader pattern: incumbents are trying to lock in capability advantages that directly affect contact reliability and design flexibility. On the qualification side, one Japanese manufacturer secured recognition as a primary supplier for 2 nm probe card solutions after co-development work with TSMC, a milestone that underscores how advanced node access can be earned through sustained collaboration rather than product announcements alone. Another Asian supplier partnered with a major assembly and test player to co-develop chiplet-ready probe cards, signaling that test strategy is increasingly extending beyond the wafer into package-level validation. On the product side, a new series of 3D/2.5D micro-electro-mechanical systems probe cards for wafer acceptance test applications has entered the market with fine-pitch and high-pin-count support, reflecting the growing need for specialized tools in advanced packaging test flows. Meanwhile, regional expansion continues, with new facility investments in Taiwan designed to address demand from AI chip testing, and other firms pursuing localized production and supply chain diversification to reduce exposure to material disruptions.
The competitive landscape is evolving along several axes at once. Integration is increasing where large suppliers absorb niche technology or complementary intellectual property to broaden their portfolios. Differentiation is sharpening around advanced node qualification, high-bandwidth memory, chiplet-related test support, and materials or design innovations that improve contact performance. New entry is difficult at the top of the market because of qualification barriers and entrenched design-ins, but opportunities remain for specialists that can serve specific applications, support regional fabs, or provide tailored solutions where standard offerings fall short. The most resilient companies are likely to be those that combine technical precision with customer co-development, regional supply visibility, and the ability to move from prototype to volume with predictable timing.
PW Consulting
Forward Outlook: Three Trends Defining the Next Three to Five Years
The first trend to watch is the deepening alignment between probe card architecture and advanced packaging roadmaps. As 3D, 2.5D, and chiplet-based designs become more common in high-value product categories, probe card solutions will need to support more intricate test interfaces and more demanding mechanical requirements. Companies that invest early in designs suited to fine-pitch, high-pin-count, and high-density test conditions will be better positioned to participate in next-generation validation cycles. The commercial opportunity here is not simply selling more cards; it is becoming embedded in test plans before production ramps begin.
The second trend is the continued rebalancing of manufacturing geography. Regional fab expansion, policy support, and supply chain risk mitigation are encouraging localized production and material diversification. Suppliers with flexible production footprints and resilient sourcing strategies will have an advantage in meeting lead-time expectations and maintaining continuity during disruption. For customers, this trend creates both optionality and complexity: multiple regional sources can reduce dependency, but they also increase the need for qualification discipline and supplier management.
The third trend is the growing premium on reliability and predictability in test supply. As probe cards become more technically specialized and more tightly coupled to advanced node and memory roadmaps, the cost of late delivery or unstable performance rises. Buyers will increasingly reward suppliers that can demonstrate consistent lead times, stable materials availability, and strong co-development processes. At the same time, trade policy and export restrictions will remain a source of uncertainty, particularly for companies operating across multiple regions. These dynamics suggest that long-term competitiveness will depend as much on operational resilience as on product performance.
Probe Card Market
Actionable Guidance for Decision Makers
For probe card manufacturers, the priority is to align technology roadmaps with where device complexity is heading, not where it has already been. That means investing in architectures and process improvements suited to advanced logic, high-bandwidth memory, and heterogeneous packaging, while also building regional production options and diversified sourcing to protect lead times. Co-development relationships with key customers should be treated as strategic assets, because qualification timing and design-in access often matter more than incremental feature lists.
For investors, the market rewards players that combine credible advanced-node capability with operational resilience. Attention should be directed toward suppliers with strong qualification momentum, clear application focus, and evidence of capacity or technology moves that anticipate AI, memory, and advanced packaging demand. Concentration in the market is high, so differentiation, proprietary technology, and regional supply strategy are important indicators of durability.
For procurement and operations leaders, the commercial task is to reduce single-point dependency without sacrificing qualification rigor. Diversifying sources can improve resilience, but it must be paired with disciplined qualification, clear lead-time expectations, and close coordination with internal test roadmaps. As advanced package and high-bandwidth memory programs become more central, early engagement with test suppliers will help reduce schedule risk and avoid last-minute constraints.
Vertical Probe Cards Market
For decision makers seeking deeper segmentation, regional breakdowns, competitive tracking, and scenario-based insight, the full PW Consulting study on the worldwide probe cards market provides expanded detail and supporting analysis to inform planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Probe Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polylaurolactam Market 2026–2032: Beyond the 5.6% CAGR Growth Trajectory
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Polylaurolactam Market
Market Overview and Core Challenges
Sizing the Opportunity
The global polylaurolactam market has demonstrated steady expansion over the past five years, with revenue scaling from approximately $1.12 billion in 2020 to $1.49 billion in 2025. Moving forward, the trajectory points toward a continuation of this upward trend, with projected revenues reaching $2.18 billion by 2032 at a compound annual growth rate of 5.6%. This growth is not merely a function of industrial expansion but reflects a structural shift in material preferences across several high-value sectors. The market's resilience stems from polylaurolactam's unique combination of chemical resistance, flexibility, and lightweighting capabilities, which make it indispensable in applications where traditional materials fall short. The consistent upward trajectory suggests that demand drivers are deeply embedded in end-user industries rather than being purely cyclical.
Three Critical Challenges Shaping the Landscape
Despite the positive growth outlook, the industry faces several structural headwinds that will define competitive positioning over the next five years. The first challenge lies in raw material volatility. Laurolactam, the primary monomer for polylaurolactam, depends on petrochemical feedstocks such as cyclododecane derived from butadiene. Fluctuations in butadiene pricing directly cascade into laurolactam and subsequent PA12 costs, creating margin pressure and pricing uncertainty. Recent data from late 2025 indicated weak to slightly declining price trends in both Asia and Europe, reflecting broader soft chemical market conditions and subdued feedstock demand. However, this softness does not eliminate structural volatility; rather, it underscores the market's sensitivity to upstream petrochemical cycles.
PW Consulting
The second challenge involves the growing emphasis on sustainability and bio-based alternatives. Automotive OEMs have set explicit targets for 20–30% sustainable polymer content by 2030, pressuring manufacturers to transition away from fully fossil-based PA12 grades. While bio-based variants exist, scaling production while maintaining cost parity remains a significant hurdle. The regulatory and commercial push toward greener materials is not a passing trend; it is becoming a prerequisite for supply chain access in certain regions and industries. Companies that fail to adapt their product portfolios to include certified sustainable grades risk marginalization as downstream customers tighten procurement criteria.
Polycaprolactone Market
The third challenge centers on geographic capacity expansion and its impact on pricing dynamics. China has been actively expanding laurolactam and Nylon 12 production capacity, which continues to influence regional pricing and competitive intensity in Asia. This capacity build-out introduces both opportunities for localized supply chain resilience and risks of oversupply in certain market segments. The interplay between new capacity coming online and the pace of demand absorption will determine whether the market experiences healthy growth or margin compression in the near term. Companies must navigate this balance carefully, as overcapacity in one region can quickly spill over into global pricing expectations.
Key Drivers Analysis
Technological Innovation and Performance Breakthroughs
Innovation in polymer compounding and processing continues to unlock new applications for polylaurolactam, extending its relevance beyond traditional segments. Advances in extrusion and injection molding grades have improved processability and reduced cycle times, making the material more attractive to manufacturers seeking efficiency gains. In additive manufacturing, the development of optimized powder grades has enabled finer resolution and improved mechanical properties in 3D-printed components. These technological refinements are not incremental; they are expanding the addressable market by lowering adoption barriers and enabling performance outcomes that were previously difficult to achieve. Manufacturers investing in tailored grade development are finding that performance differentiation translates directly into premium pricing opportunities and longer-term customer relationships.
Regulatory and Policy Pressures
Policy frameworks are increasingly shaping procurement decisions, particularly in the automotive and industrial sectors. The push for sustainable polymer content is not limited to voluntary commitments; it is being codified into supplier qualification requirements and internal procurement standards. Regulatory attention to carbon footprint disclosure and circular economy principles is also raising the compliance bar for polymer suppliers. Companies that proactively develop bio-based grades and establish transparent lifecycle assessments are positioning themselves advantageously. The regulatory environment creates a dual dynamic: it raises the cost of compliance for laggards while offering first-mover advantages to those who can meet sustainability targets without sacrificing performance or cost competitiveness. The timing of policy implementation matters, as early alignment with emerging standards reduces the risk of sudden supply chain disruptions.
Demand-Side Shifts in End-Use Industries
End-user industries are recalibrating their material choices based on performance, cost, and sustainability considerations. Automotive and transportation applications remain the largest demand driver, supported by lightweighting initiatives and the need for durable fuel lines, tubing, and under-the-hood components. Oil and gas applications continue to rely on PA12's chemical resistance for downhole and pipeline systems, though capital expenditure cycles in this sector introduce variability. Meanwhile, electronics and electrical applications are growing as miniaturization and thermal management requirements favor high-performance polymers. A particularly notable shift is the uptake of 3D printing and additive manufacturing, where polylaurolactam powders are gaining traction for prototyping and low-volume production runs. Medical and consumer goods applications, though smaller in absolute terms, benefit from PA12's biocompatibility and flexibility in specific formulations. The demand picture is becoming more diversified, reducing reliance on any single sector and creating multiple growth vectors.
Worldwide Lauryl Acrylate Market
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by feedstock dynamics, capacity geography, and production scale. The dependence on butadiene-derived cyclododecane means that laurolactam economics are tightly coupled to broader petrochemical markets. When butadiene prices are volatile, PA12 producers face difficult decisions around pricing, inventory management, and margin protection. At the same time, capacity expansions in Asia are altering the regional cost landscape, offering lower production costs in some areas but also intensifying competition. Integrated producers that control upstream feedstocks or operate at significant scale benefit from cost advantages and greater pricing flexibility. Conversely, smaller or more fragmented players may struggle to absorb volatility without eroding margins. The supply chain is also seeing increased attention to logistics and regional supply security, as customers seek to reduce exposure to long-distance dependencies and geopolitical disruptions.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market is highly concentrated, with a small group of global players commanding the majority of revenue. This concentration reflects the capital intensity of production, the technical expertise required for grade development, and the long-term supply relationships typical of high-performance polymer procurement. Leading producers have built their positions on a combination of scale, product breadth, and application-specific expertise. Evonik Industries AG anchors its strategy around large-scale PA12 production at its Marl Chemical Park, positioning itself as a reliable supplier for automotive, industrial, and 3D printing applications. Its sustainability-focused initiatives highlight efforts to align high-performance polymer production with evolving environmental expectations, reinforcing its appeal to customers prioritizing responsible sourcing. Arkema SA differentiates through its Rilsan PA12 portfolio, with particular emphasis on bio-based variants and specialty grades for tubing, fuel lines, and high-performance applications. This focus on sustainability-linked differentiation aligns directly with automotive OEM targets and positions Arkema as a strategic partner for customers navigating material transitions.
EMS-Chemie Holding AG has established a strong footprint through its Grilamid PA12 resins and compounds, targeting engineering applications across automotive, electronics, and industrial components. Its strategy emphasizes formulation flexibility and application support, enabling customers to optimize material performance for specific use cases. UBE Corporation supplies UBE Nylon 12 grades with a focus on precision molding and industrial uses, leveraging its Asia-Pacific production capabilities to serve regional demand efficiently. Its geographic positioning supports customers who prioritize responsive local supply and technical service. Wanhua Chemical operates as an integrated producer offering a full range of PA12 products for domestic and export markets. Its recent price increases of 5%–10% across its product range reflect a willingness to adjust pricing in response to market conditions and cost dynamics, signaling a more assertive commercial posture.
Market Structure Evolution
The competitive landscape is likely to evolve along multiple dimensions. Consolidation remains a plausible path as scale advantages become more pronounced and investment requirements for capacity and innovation grow. At the same time, differentiation is intensifying across product grades, sustainability credentials, and application support. New entrants face high barriers, but regional capacity additions, particularly in Asia, are altering the competitive balance by increasing supply options and pressuring pricing in certain segments. The market is not simply tightening around incumbents; it is becoming more stratified, with premium segments rewarding performance and sustainability innovation while commodity-adjacent segments face margin pressure. Companies that can navigate both dimensions—maintaining cost discipline while advancing differentiated offerings—are best positioned to capture value as the market matures. Strategic partnerships and vertical integration are also emerging as levers to secure feedstock access, improve cost predictability, and accelerate the development of sustainable grades.
Future Trends and Commercial Opportunities
Trend 1: Sustainability-Linked Product Segmentation
The market is moving toward clearer segmentation between conventional and sustainable PA12 grades. As automotive and industrial buyers embed sustainability targets into procurement, demand for bio-based and lower-carbon variants will grow even if these grades carry a premium. This creates an opportunity for producers to develop certified product lines, establish transparent lifecycle data, and secure long-term supply agreements with sustainability-conscious customers. The risk lies in the pace of cost reduction for bio-based production; if premiums remain high without clear value recognition from buyers, adoption may slow.
Trend 2: Additive Manufacturing as a Growth Accelerator
3D printing and additive manufacturing are expanding the use profile of polylaurolactam beyond traditional molding and extrusion. Powder-grade optimization, combined with growing adoption in prototyping, tooling, and low-volume production, offers a new demand channel that can be more responsive to innovation cycles than large-scale industrial procurement. Companies that invest in powder-grade development and application support for additive workflows can capture higher-margin segments and build relationships with users who may later scale into broader production applications. The uncertainty here relates to the pace of industrial adoption versus prototyping use; if additive applications remain primarily niche, the growth upside may be more limited than current enthusiasm suggests.
Trend 3: Regional Capacity Rebalancing and Pricing Dynamics
Asia's continued expansion in laurolactam and PA12 capacity will reshape regional supply and pricing dynamics. This can benefit customers seeking cost-effective supply and reduce dependency on distant sources, but it also introduces the possibility of localized oversupply and intensified competition. Producers outside Asia may need to emphasize service, technical support, and differentiated grades to maintain share, while Asian producers will need to balance capacity utilization with pricing discipline. For commercial players, this trend creates opportunities in regional supply chain optimization, import/export positioning, and strategic sourcing that accounts for shifting cost bases.
Strategic Recommendations for Decision-Makers
For Manufacturers and Producers
- Accelerate the development and commercialization of bio-based and lower-carbon PA12 grades to align with automotive and industrial sustainability targets before regulatory and procurement pressures become more binding.
- Invest in grade-level differentiation for additive manufacturing and high-performance applications to capture premium segments and reduce exposure to commodity-like pricing pressure.
- Evaluate supply chain and feedstock strategies to improve cost predictability, including long-term supplier agreements, vertical integration where feasible, and regional production positioning that matches demand geography.
For Investors
- Prioritize companies with clear sustainability roadmaps and application-specific differentiation, as these traits are likely to command valuation support and customer loyalty in a market increasingly shaped by procurement criteria beyond price alone.
- Monitor capacity additions in Asia and their impact on regional pricing, as oversupply risk could compress margins for undifferentiated products while creating acquisition or partnership opportunities for well-positioned players.
- Assess exposure to additive manufacturing and high-growth application segments as potential upside drivers, but calibrate expectations against the pace of industrial adoption.
For Procurement and Supply Chain Leaders
- Diversify supplier bases to hedge against regional capacity shifts and feedstock volatility, while ensuring that alternative sources can meet performance and sustainability specifications.
- Engage suppliers early on bio-based and sustainable grade availability, securing visibility on timelines, certifications, and cost implications to avoid last-minute constraints as internal targets tighten.
- Build technical collaboration into procurement relationships, using application support and grade optimization to improve total cost of ownership rather than focusing solely on unit price.
Looking Ahead
The polylaurolactam market is at an inflection point where steady growth intersects with structural changes in sustainability expectations, application expansion, and regional capacity dynamics. For decision-makers, the imperative is to look beyond headline demand figures and understand how grade differentiation, feedstock volatility, and sustainability mandates will reshape competitive advantage. Detailed segmentation data, regional pricing analysis, and company-level benchmarking provide the granularity needed to translate these trends into actionable strategy. Readers interested in a comprehensive breakdown of market size by segment, competitive positioning, and customized scenario analysis can explore the full research report for deeper insights and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Polylaurolactam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Elastomeric Polyurethane Roof Coating: How 6.8% CAGR and Asia Pacific Growth Redefine Markets
By pmarketresearch, 2026-09-18
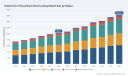
Worldwide Elastomeric Polyurethane Roof Coating Market: Strategic Trends and Commercial Opportunities
Market Overview & Core Challenges
The global elastomeric polyurethane roof coating market has solidified its position as a critical segment within the broader construction chemicals and waterproofing industry. Valued at approximately 1,025.4 million USD in 2025, the market reflects a compound annual growth rate of 6.8 percent across the forecast horizon extending to 2032. This trajectory underscores a steady, resilient expansion pattern, driven by the inherent performance advantages of elastomeric polyurethane systems, including exceptional flexibility, UV resistance, crack-bridging capabilities, and seamless application profiles. The historical growth from 745.2 million USD in 2020 to the current baseline demonstrates consistent demand absorption across developed and emerging construction ecosystems, while the projected climb toward 1,625.15 million USD by 2032 signals a maturing but still highly dynamic commercial landscape.
Despite the favorable macroeconomic tailwinds, the industry currently navigates several structural inflection points that demand strategic recalibration. First, raw material price volatility remains a persistent operational headwind. The polyurethane value chain relies heavily on methyldiphenyl diisocyanate (MDI) and polyol feedstocks, both of which are subject to periodic supply-demand imbalances, energy cost fluctuations, and geopolitical trade realignments. Recent pricing data indicates that MDI prices in the United States fell to 1,890 USD per metric ton in August 2025, marking a 13 percent month-over-month decline and a 19 percent year-over-year drop. While such declines temporarily ease input cost pressures, they often coincide with broader market uncertainty and can compress margins for formulators who have already locked in higher procurement costs. Conversely, early 2026 announcements from major chemical producers signaling price increases for MDI and polyols highlight how quickly cost structures can shift, leaving manufacturers and distributors vulnerable without robust hedging strategies or flexible formulation architectures.
Second, the regulatory environment around fluorinated compounds and volatile organic compounds (VOCs) continues to tighten, particularly in North America and Europe. The U.S. Environmental Protection Agency (EPA) has advanced its hydrofluorocarbon (HFC) phasedown agenda, implementing import prohibitions on certain products containing HFCs effective January 2025 under the AIM Act Technology Transitions Program. While HFC restrictions primarily target refrigerant-based applications, the broader regulatory momentum influences polyurethane formulation philosophies, pushing formulators toward low-VOC, solvent-free, and bio-based alternatives. Compliance with evolving VOC limits, particularly in states with stringent air quality mandates, requires sustained R&D investment and can temporarily disrupt traditional product roadmaps. Third, the market exhibits moderate concentration dynamics, with the top three players capturing roughly 38.45 percent of total revenue and the top five accounting for approximately 52.1 percent. This concentration reflects the technical barriers to entry, established specification networks, and long-standing contractor relationships that incumbents have cultivated. However, it also creates space for specialized challengers and regional specialists who can differentiate through niche performance claims, localized service models, or faster customization cycles.
These challenges are not insurmountable, but they do reframe the competitive calculus. Companies that treat raw material volatility as a purely reactive cost issue rather than a strategic sourcing and formulation opportunity risk lagging behind peers who build flexibility into their supply chains and portfolio architectures. Similarly, regulatory tightening is best viewed not as a compliance burden but as a catalyst for product modernization and market differentiation. The market's expansion to 1,625.15 million USD by 2032 will not be evenly distributed; it will accrue to organizations that can align product innovation, regulatory readiness, and supply chain resilience with the evolving requirements of specifiers, contractors, and building owners.
Key Growth Drivers
Technological Innovation and Formulation Advancements
The core performance proposition of elastomeric polyurethane roof coatings continues to be reinforced by targeted technological advances. Formulators are increasingly differentiating through aliphatic versus aromatic system architectures, moisture-cure versus two-component curing mechanisms, and the integration of UV-stable top coats that extend service life on exposed substrates. The shift toward low-odor, low-VOC, and solvent-free formulations addresses both regulatory pressure and on-site application preferences, particularly in urban retrofits where ventilation constraints and occupant sensitivity limit the use of high-solvent products. Product line expansions that pair aromatic base coats with aliphatic top coats exemplify a practical engineering approach: the base coat delivers adhesion, crack-bridging, and moisture tolerance, while the top coat provides long-term UV stability and color retention. Recent specification updates from industry participants illustrate how these technical nuances translate into commercial value. In mid-2025, a major coating manufacturer released updated restoration specification guidance for elastomeric polyurethane systems applied over ethylene propylene diene monomer (EPDM) membranes, reinforcing the role of compatible, high-performance top coats in extending the service life of existing roof assemblies. Shortly thereafter, the same company updated availability and specification details for its aromatic base coat and aliphatic top coat systems in standard pack sizes, signaling a focus on specification clarity and contractor accessibility. Such moves highlight how formulation precision, specification support, and packaging flexibility collectively strengthen market positioning.
Policy, Regulation, and Building Performance Mandates
Regulatory and policy environments are reshaping demand patterns by elevating the importance of durability, sustainability, and indoor air quality in roof restoration decisions. Building code updates, energy efficiency targets, and local air quality regulations are pushing specifiers toward coatings that minimize VOC emissions while maintaining elongation, tensile strength, and reflectivity over extended service intervals. The ongoing HFC phasedown and related technology transition initiatives may not directly govern elastomeric polyurethane coatings in all cases, but the regulatory trajectory reinforces a broader market expectation: building materials must demonstrate environmental responsibility without compromising performance. This expectation advantages formulators that can document low VOC content, reduced odor profiles, and compatibility with green roof assemblies or cool roof reflectance goals. Additionally, public infrastructure spending and municipal retrofit programs increasingly favor liquid-applied, seamless waterproofing systems that reduce leak pathways and minimize disruption during application. The alignment between regulatory direction and product capability creates a durable demand pull, particularly in regions where aging roof stock and stringent performance standards coincide.
Demand-Side Shifts in Commercial and Industrial Sectors
End-user behavior is evolving along two principal axes: lifecycle cost consciousness and maintenance minimization. Commercial building owners and facility managers are increasingly treating roof coatings as a capital-efficient alternative to full membrane replacement, especially where structural deck conditions remain sound and the primary failure modes involve surface degradation, seam fatigue, or minor cracking. Elastomeric polyurethane systems appeal in this context because they conform to substrate movement, bridge hairline cracks, and reduce the likelihood of water intrusion without the demolition and disposal costs associated with tear-off projects. In industrial facilities, heavy mechanical traffic, chemical exposure, and thermal cycling demand coatings that combine flexibility with abrasion resistance and chemical tolerance. The market's application mix reflects this reality, with commercial buildings representing the largest demand pool, followed by residential construction and industrial facilities. Residential demand is gaining traction as homeowners and multifamily property managers seek cost-effective weatherproofing solutions that extend roof service life and improve energy performance. Across these segments, the specification decision is increasingly influenced by total installed cost, downtime reduction, and long-term maintenance predictability rather than initial material price alone.
Supply Chain Dynamics and Cost Structure Evolution
The polyurethane feedstock landscape is undergoing a period of recalibration that will influence competitive positioning through the forecast period. Global MDI and TDI prices remained broadly stable through 2025, with a cautious outlook for stabilization in 2026 driven by supply-side adjustments. This stability provides a window for formulators to optimize formulation economics, lock in supplier agreements, and invest in alternative feedstock strategies without the urgency of acute price spikes. However, trade policy introduces a significant variable. The United States has imposed escalating tariffs on Chinese-origin MDI, starting at 30 percent and reaching 145 percent, with potential further antidumping duties under review through March 2026. These measures affect polyurethane feedstock costs and may restructure sourcing patterns, encouraging regional supply diversification, inventory buffering, and closer integration with non-affected feedstock sources. The interplay between feedstock price stabilization and tariff-driven cost pressure creates a bifurcated operating environment: companies with diversified supplier bases, transparent cost pass-through mechanisms, and agile formulation portfolios are better positioned to maintain margin integrity, while those reliant on single-source or tariff-exposed supply chains face greater exposure to cost shocks. This dynamic also elevates the strategic importance of bio-based polyols and alternative isocyanate pathways as medium-term levers for supply resilience and sustainability storytelling.
Competitive Landscape & Leading Strategies
The competitive architecture of the elastomeric polyurethane roof coating market is defined by a blend of multinational specialty chemical groups, focused regional manufacturers, and application-oriented solution providers. This mix produces a landscape where technical credibility, specification relationships, and service reliability often outweigh pure price competition. Several incumbent profiles illustrate the strategic diversity shaping the market.
Sika Corporation maintains a broad, globally integrated platform spanning liquid-applied roofing and waterproofing systems. Its product architecture includes single-component low-odor polyurethane roof coatings and two-component, fast-curing, solvent-free base coats designed for crack-bridging and elastomeric performance. Sika's strategic positioning rests on scale, specification depth, and the ability to offer compatible resin systems across multiple waterproofing platforms. This breadth supports large-scale commercial and infrastructure programs where consistent performance documentation, technical service, and supply reliability are critical differentiators. Polycoat Products has carved a focused position around polyurethane coatings and elastomer solutions for waterproofing, emphasizing UV resistance, durability, and waterproofing performance for roof and deck applications. Its strategy highlights specialization: by concentrating on elastomeric polyurethane membranes and coatings for demanding substrates, Polycoat builds reputation equity among contractors and specifiers who prioritize application-specific performance over broad portfolio breadth.
Inland Coatings, Inc. exemplifies a specification-driven, product-clarity approach. Its AldoThane series pairs aromatic base coats with aliphatic UV-stable top coats to deliver seamless, flexible waterproof membranes across diverse roof substrates. Recent activity underscores the importance of specification support and product availability: updated specifications for restoration over EPDM membranes and refreshed availability details for core product sizes demonstrate how incumbents reinforce market presence by reducing specification friction and ensuring reliable access to proven systems. Tremco Commercial Sealants & Waterproofing brings a complementary angle through one-part moisture-triggered polyurethane roof coatings and exploration of bio-based polyurethane options for reinforced liquid-applied roofing systems. This trajectory signals a dual emphasis on application convenience and sustainability-aligned innovation, appealing to project teams that value simplified application logistics alongside evolving environmental expectations.
Other participants deepen the market's regional and application-specific texture. Urethane Polymers International, Inc. focuses on elastomeric single-component systems engineered for low-slope roofing under heavy mechanical and pedestrian traffic, an area where abrasion resistance and recoatability are decisive. Karnak Corporation and Stockmeier Urethanes USA supply elastomeric polyurethane coatings that serve as practical, specification-friendly options for restoration and maintenance programs. American WeatherStar emphasizes high-solids, moisture-cure formulations primarily for sprayed polyurethane foam roofing protection and related commercial substrates, aligning product design with the specific thermal and protective needs of foam-based assemblies. In parallel, manufacturers such as Hebei Ruide Building Waterproof Material Co., Ltd. reflect the broader internationalization of supply capability, producing polyurethane roof coatings with an emphasis on durability and performance in elastomeric applications, which contributes to cost-competitive pressure and expanding option sets for price-sensitive markets.
The market's evolution is trending toward both consolidation of technical authority and fragmentation of niche advantage. On one hand, larger players with integrated R&D, global supply networks, and extensive specification libraries are well positioned to capture share in complex commercial and infrastructure programs. On the other hand, specialized manufacturers that deliver clear performance claims, rapid customization, and strong regional service can defend and expand their positions by reducing specification risk for contractors and building owners. New entrants and smaller formulators are most likely to succeed when they target underserved substrate types, specific climate durability requirements, or application formats that larger portfolios treat as secondary. The recent product and specification activity across several incumbents also suggests a market where clarity of use cases, compatibility documentation, and availability matter as much as raw performance metrics. Companies that streamline the path from specification to procurement to application will capture disproportionate value in a market where installation quality and long-term service life are central to customer satisfaction.
Future Outlook & Strategic Implications
Over the next three to five years, the elastomeric polyurethane roof coating market is likely to trend along three reinforcing directions. First, low-VOC, solvent-free, and bio-based formulation pathways will move from differentiating features to baseline expectations in many specification contexts. As regulatory momentum continues and contractor/occupant sensitivity to odor and emissions grows, formulators that can deliver strong elongation, adhesion, and UV stability within constrained VOC profiles will secure preferential positioning in commercial and institutional bids. This trend creates commercial opportunity for companies that invest early in formulation validation, performance documentation, and specifier education, particularly where green building programs and local air quality rules intersect.
PW Consulting
Second, supply chain reconfiguration will become a more explicit competitive lever. Tariff dynamics on certain MDI sources, combined with periodic feedstock price volatility, will encourage regional sourcing diversification, strategic inventory positioning, and closer collaboration with suppliers on forecasting and allocation. Organizations that build transparent cost-pass-through frameworks and maintain formulation flexibility will be better equipped to manage margin pressure without sacrificing specification credibility. This environment also elevates the value of alternative feedstock strategies, including bio-based polyols and regionally balanced supply mixes, both as cost-risk mitigation tools and as sustainability narrative enhancers.
Third, the restoration and maintenance segment will expand as a share of total demand, driven by aging roof stock, capital constraints, and the attractiveness of liquid-applied systems that avoid tear-off disruption. Elastomeric polyurethane coatings are well aligned with this shift because they accommodate substrate movement, bridge cracks, and extend service life with comparatively low installation intrusion. Commercial buildings will remain the dominant application pool, but industrial facilities and residential multifamily projects offer meaningful upside where durability, traffic resistance, and weatherproofing performance are prioritized. The opportunity lies in pairing product performance with specification support, compatibility guidance, and field service that reduces installation risk and protects long-term outcomes.
Potential risks and uncertainties deserve attention. Feedstock cost volatility can reemerge quickly, especially if energy markets shift or trade measures intensify, compressing margins for companies without flexible procurement or pricing strategies. Regulatory trajectories may accelerate in certain jurisdictions, creating uneven compliance burdens and requiring formulation agility across regions. Competitive intensity could increase if new entrants or imported supply press price points in price-sensitive segments, potentially eroding differentiation if incumbents rely too heavily on historical specification relationships. Finally, macroeconomic fluctuations in construction activity can affect the timing and scale of retrofit programs, making demand forecasting more variable. These uncertainties do not diminish the market's growth potential, but they reinforce the importance of scenario planning, supply resilience, and product-portfolio flexibility.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align formulation roadmaps with emerging specification expectations while building supply chain options that reduce exposure to feedstock and tariff shocks. Invest in low-VOC, solvent-free, and compatible base/top-coat system architectures, and pair product launches with clear compatibility documentation and specification support that reduces risk for contractors and specifiers. Diversify feedstock sourcing, evaluate alternative polyol and isocyanate pathways where feasible, and develop pricing mechanisms that preserve margin integrity during cost swings without undermining bid competitiveness.
Polyurea Coatings Market
For investors, focus on companies that demonstrate technical differentiation, specification momentum, and supply resilience rather than those competing primarily on price. Look for portfolios that combine proven elastomeric performance with clear regulatory readiness and application flexibility, and assess whether target companies have strong regional service capabilities and repeatable specification wins in commercial restoration and industrial maintenance. In a market projected to expand steadily through 2032, sustainable advantage will accrue to firms that can convert product performance into specification trust and installation reliability.
For procurement and asset owners, prioritize total lifecycle value over initial material cost. Evaluate coatings based on compatibility with existing substrates, UV stability, elongation and crack-bridging performance, VOC profile, and the quality of specification and field support available from the manufacturer. Where possible, consolidate product relationships with suppliers that can provide consistent performance documentation, clear application guidance, and reliable availability, reducing project risk and protecting long-term roof performance.
As the market evolves, detailed segmentation data, regional demand nuances, and customized strategic guidance become increasingly valuable for precise decision-making. PW Consulting's full research report provides deeper breakdowns and tailored recommendations for manufacturers, investors, and procurement teams seeking to navigate this dynamic landscape with confidence.
Roof Coating Market
For detailed analysis of this topic, please visit the official page: Worldwide Elastomeric Polyurethane Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
POE Synthetic Materials Market: Why 9.5% CAGR Reshapes Global Competition Through 2032
By pmarketresearch, 2026-09-18
Navigating the Polyolefin Elastomer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global polyolefin elastomer (POE) market has entered a phase of accelerated structural growth, with total revenue climbing from approximately $2.75 billion in 2020 to a projected $4.2 billion in 2025. This upward trajectory is expected to sustain a compound annual growth rate of 9.5 percent through 2032, pushing the market toward the $7.9 billion mark. The expansion reflects a broader industrial shift toward high-performance, lightweight, and durable polymeric materials that can replace heavier or less versatile alternatives across demanding applications.
Despite the favorable momentum, three structural challenges are reshaping how manufacturers, converters, and downstream buyers approach the POE value chain. First, feedstock volatility remains a persistent earnings and pricing risk. Production costs are heavily influenced by ethylene, propylene, and alpha-olefin derivatives, with pricing swings tied to crude oil movements, refinery maintenance cycles, and regional demand imbalances. A notable example occurred in mid-2025, when U.S. ethylene prices rose sharply amid scheduled refinery maintenance and strong Asian demand, creating upward pressure on extrusion-grade material costs and squeezing margins for price-sensitive converters.
Worldwide Propylene Based POE Market
Second, regional capacity dynamics are altering trade flows and competitive intensity. Significant expansion projects in China, driven by domestic producers, have brought total POE capacity to substantial scale by late 2025. Import volumes of ethylene alpha-olefin copolymers declined markedly year-on-year during the first ten months of the year as localized supply began to displace imported grades, particularly for photovoltaic encapsulant applications. This localization wave is compressing premiums for imported specialty grades and forcing global suppliers to recalibrate regional pricing, service models, and value proposition positioning.
Third, the market exhibits high concentration, with a small group of incumbent producers controlling the majority of global supply. This concentration provides scale advantages in catalyst technology, grade development, and customer qualification, but it also creates vulnerability for converters and end-users who depend on a limited supplier base for critical grades. Supply disruptions, grade transitions, or shifts in producer priority can quickly cascade into production bottlenecks or qualification delays for downstream manufacturers.
For decision-makers, these challenges translate into a clear mandate: pricing resilience, supply diversification, and grade-level differentiation are no longer optional. Businesses that treat feedstock exposure, regional capacity shifts, and supplier concentration as strategic variables, rather than operational noise, will be better positioned to protect margins and secure reliable access to performance-critical elastomer grades.
Key Demand Drivers
The 9.5 percent growth trajectory is not accidental; it is anchored in a convergence of technology, regulation, demand-side behavior, and supply chain evolution that is reinforcing POE adoption across multiple end-use sectors.
Catalyst and Polymer Architecture Innovation
POE production relies on the copolymerization of ethylene with octene or butene, typically using metallocene catalysts that deliver precise control over molecular architecture. Advances in catalyst design and process control have expanded the performance envelope of POE grades, enabling superior impact resistance, elasticity, thermal sealing behavior, and compatibility with polyethylene and polypropylene blends. These technical improvements allow formulators to replace multiple SKUs with single, multifunctional grades, simplifying compounding operations while meeting tighter performance specs for automotive components, wire and cable, and packaging.
Recent commercial milestones illustrate how innovation is translating into market share. Dow introduced bio-attributed ENGAGE REN polyolefin elastomers for flooring applications, leveraging bio-circular feedstocks such as used cooking oil and ISCC PLUS mass-balance certification. This launch signals a broader shift toward integrating sustainability attributes directly into high-performance elastomer portfolios, rather than treating environmental credentials as an afterthought. ExxonMobil’s unification of its polyolefin products under the Signature Polymers brand reinforces a service and partnership model designed to streamline customer engagement across elastomer and broader polyolefin offerings.
Regulatory and Environmental Pressures Accelerating Adoption
Tighter environmental regulations for automobiles are a powerful catalyst for POE demand. Lightweighting initiatives aimed at improving fuel efficiency, controlling emissions, and reducing fuel permeation are driving formulators toward elastomers that deliver strength and flexibility at lower part weight. POE’s ability to enhance impact performance in thermoplastic olefins and to improve processability in blends makes it a preferred modifier in automotive bumpers, interior components, and sealing systems. Concurrently, renewable energy deployment is expanding the addressable market for POE in photovoltaic encapsulant films, where clarity, durability, and long-term weatherability are critical to module lifetime and energy yield.
Demand-Side Shifts in Automotive, PV, and Industrial Applications
On the demand side, two macro trends are reshaping purchasing behavior. In automotive, the push toward electrification and stricter emissions frameworks is accelerating material substitution programs, with engineers prioritizing components that reduce mass without compromising crash performance or noise, vibration, and harshness characteristics. In parallel, the photovoltaic sector continues to scale module production globally, and encapsulant film demand is growing in lockstep with capacity additions and the transition to higher-efficiency cell architectures. Industrial and consumer applications, including wire and cable, hygiene products, and easy-peel packaging, are also benefiting from POE’s versatility in improving flexibility, sealability, and surface properties.
Supply Chain Realignment and Cost Structure Evolution
Supply chain dynamics are undergoing a structural realignment. Feedstock price volatility, refinery maintenance schedules, and regional demand imbalances are prompting producers and converters to rethink sourcing strategies. At the same time, capacity additions in key Asian markets are reducing reliance on imported grades for certain applications, while global incumbents are investing in differentiated portfolios and sustainability-certified offerings to preserve pricing power. The combined effect is a market where cost leadership alone is increasingly insufficient; competitors must pair operational efficiency with grade-level performance, sustainability credentials, and reliable regional service to win and retain share.
Competitive Landscape and Leading Strategies
The POE market is defined by a concentrated set of global producers, each pursuing distinct positioning strategies that reflect their catalyst capabilities, application focus, and regional footprint. Understanding these strategies is essential for buyers evaluating supply security and for competitors assessing where differentiation is still achievable.
Incumbent Positioning and Differentiation Levers
Dow remains the largest global producer of POE, with a comprehensive portfolio spanning ethylene-octene and ethylene-butene copolymers for automotive TPO compounds, wire and cable, packaging, and photovoltaic encapsulants. Its differentiation rests on breadth of grades, application-specific performance tuning, and a growing sustainability narrative through bio-attributed offerings. ExxonMobil Chemical leverages its Exact and Vistamaxx performance polymer families to serve impact modification, flexible packaging, and compounding applications, emphasizing product unification and customer service through its Signature Polymers brand initiative.
Mitsui Chemicals, alongside partners such as Idemitsu Kosan and Sumitomo Chemical, is consolidating polypropylene and LLDPE businesses into Prime Polymer Co., Ltd., with integration effective in 2026 and targeted synergies exceeding 8 billion yen through facility consolidation and enhanced high-performance polyolefin capabilities. This move underscores a regional strategy of scale and integration to strengthen competitiveness in high-value polyolefin segments. LG Chem differentiates with LUCENE POE, produced using proprietary metallocene catalysts to deliver impact resistance, elasticity, low thermal sealing, and applications in automotive sound insulation and shock-absorbing parts. SABIC, through its joint venture structure, supplies Fortify POE grades focused on impact modification, processability, and durability for automotive and packaging uses.
Borealis, LyondellBasell, Braskem, Arkema, Sumitomo Chemical, Chevron Phillips, and INEOS each occupy specialized niches. Borealis emphasizes Queo POE for wire and cable, solar, and automotive sealing applications, with a focus on compounding performance. LyondellBasell tailors grades for automotive and packaging impact and flexibility enhancement. Braskem highlights sustainable and bio-based POE solutions. Arkema, Sumitomo Chemical, Chevron Phillips, and INEOS round out the field with specialty material support, high-quality elastomer R&D, and industrial compounding grades. Collectively, these players illustrate a market where differentiation increasingly hinges on application engineering, sustainability certification, and regional service reliability rather than commodity pricing alone.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The competitive landscape is evolving along three axes. First, consolidation is accelerating in regions where scale and feedstock integration can unlock cost and capability advantages, as evidenced by the Mitsui-Idemitsu-Sumitomo integration effort and similar facility rationalization discussions across the industry. Second, fragmentation persists at the grade and application level, where specialty formulations for photovoltaic encapsulants, automotive lightweighting, and medical or industrial uses require dedicated development and qualification pathways. Third, new entrants and capacity expansions in Asia are reshaping regional supply-demand balances, intensifying competition for import-substituted grades while creating opportunities for global suppliers that can offer differentiated performance or sustainability attributes not easily replicated at scale.
PW Consulting Chemical & Energy Research Center
For buyers, the implication is clear: supplier selection should weigh not only price and availability, but also grade-level technical support, qualification risk, sustainability certification, and regional service density. For producers, the path to durable share gains lies in pairing scale with application-specific innovation and credible sustainability claims that resonate with regulated end markets.
Future Outlook and Strategic Opportunities
Looking ahead to the 2026–2032 window, three trends are likely to define the POE market and create actionable opportunities for well-positioned stakeholders.
First, sustainability-integrated POE will move from niche to mainstream in selected applications. Bio-attributed and mass-balance-certified grades are already entering commercial portfolios, and as automotive emissions rules tighten and consumer goods brands pursue circular material goals, demand for verified sustainable elastomers is expected to rise. The opportunity lies in securing qualified sustainable grades early, building traceability and certification capabilities, and aligning product development with downstream brand and regulatory requirements. The risk is that certification complexity and feedstock availability could constrain supply or create premium volatility if not managed proactively.
Polyolefin Elastomers (POE) Market
Second, regional capacity localization will continue to compress import dependence in key markets, particularly for photovoltaic encapsulant grades and certain automotive and packaging applications. This trend creates both threat and opportunity. Converters and end-users can benefit from shorter supply chains and reduced import exposure, but global suppliers must adapt by offering grades or services that are not easily duplicated locally, such as advanced impact modification, high-clarity encapsulant formulations, or tightly controlled compounding performance. The uncertainty lies in the pace and scale of localization, which could accelerate further if trade dynamics or feedstock advantages shift.
Third, feedstock cost volatility will remain a central margin driver, with ethylene and propylene pricing sensitive to crude trends, refinery maintenance, and regional demand swings. Businesses that build hedging strategies, flexible sourcing frameworks, and grade-level cost transparency will be better equipped to navigate price spikes and protect competitiveness. The upside opportunity is for producers and converters that can pass through value-based differentiation—performance, sustainability, or service—rather than competing solely on commodity price.
These trends converge on a central theme: the POE market is transitioning from a volume-driven expansion to a value-driven competition where differentiation, resilience, and sustainability determine long-term winners. Companies that anticipate grade-level demand shifts, invest in qualification-ready sustainable portfolios, and design sourcing strategies around regional capacity dynamics will capture disproportionate value as the market matures.
Actionable Recommendations for Decision-Makers
For manufacturers and compounders, the priority is to reduce qualification risk while expanding grade flexibility. Map critical POE grades to application requirements, secure secondary sources for high-impact or encapsulant-critical grades, and align product development with sustainability-certified options where end-market regulations or customer pledges demand verified attributes. Build technical service partnerships that can accelerate grade transitions and troubleshooting, especially as regional capacity shifts alter availability patterns.
For investors, focus on value-chain positions that benefit from differentiation rather than pure volume. Favor producers and converters with strong application engineering, catalyst or grade-level IP, credible sustainability certification, and regional service density. Monitor consolidation moves and capacity additions that could reshape regional pricing power, and assess exposure to feedstock volatility relative to pricing flexibility and value-based differentiation.
For procurement and supply chain leaders, treat POE sourcing as a strategic function rather than a transactional purchase. Diversify by grade and region, quantify feedstock exposure in cost models, and embed sustainability and certification requirements into supplier selection criteria. Align inventory and qualification plans with expected localization trends to balance cost efficiency against supply resilience.
Detailed segment-level data, regional capacity trajectories, and customized sourcing and investment recommendations are available in the full PW Consulting research report on the PolyOlefin Elastomer market.
For detailed analysis of this topic, please visit the official page: PolyOlefin Elastomer (POE) Synthetic Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com